Disability Insurance for Quantitative Analysts
Income Protection for Quantitative Analysts
Quantitative Analyst Disability Coverage & Income Protection
Coverage Built Around Performance-Linked Bonus Income
Set for Life Insurance is an independent disability insurance brokerage, not a life insurance, estate-planning, or cash-value product. Individual disability insurance for quantitative analysts replaces income a base-salary-only group plan was never built to see. Bonus tied to a model’s live results or a strategy’s realized performance, along with deferred compensation earned but not yet paid, moves on a separate track from base salary, while a standard employer plan calculates its benefit from base pay alone. Individual coverage, underwritten to actual earned income rather than a flat plan ceiling, insures the share of compensation the group plan leaves out.
Compare Carriers for Quantitative Analysts
Income Protection for Quantitative Analysts
"*" indicates required fields
Quantitative Analyst Disability Insurance, Compared
What Individual Disability Insurance Covers for Quantitative Analysts
This page is for a quantitative analyst shopping for individual income protection, not one pursuing a denied claim. It covers the buying decision only, not how to prove or appeal a claim after a disability occurs.
Individual disability insurance for quantitative analysts, sometimes called income protection, is a personally owned policy replacing income when a quant building statistical arbitrage models, running algorithmic trading strategies, or practicing financial risk management cannot perform their occupation. It is structured separately from any group long-term disability plan a bank, hedge fund, asset manager, or trading firm provides, and it carries through a firm closure or a career move. Coverage is non-cancellable and guaranteed renewable to a stated age, so the carrier cannot cancel it or raise the premium.
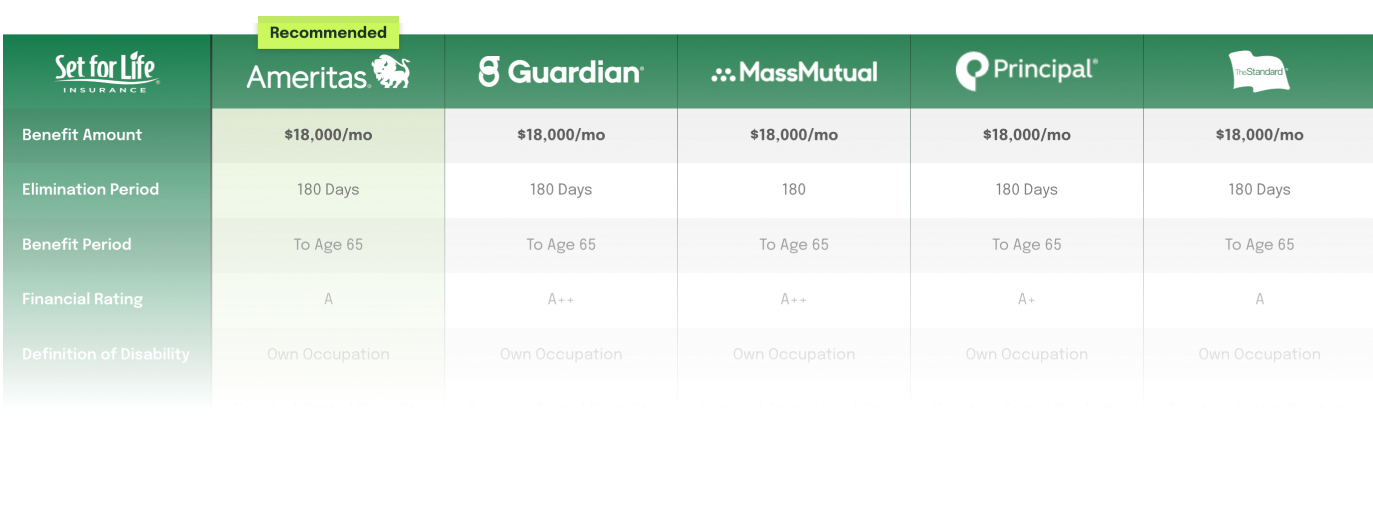
Five carriers underwrite individual disability insurance for quantitative analysts. Ameritas (Ameritas Life Insurance Corp., policy form 4501NC), Guardian (Berkshire Life Insurance Company of America, policy form ICC16 18ID Provider Choice), MassMutual (Massachusetts Mutual Life Insurance Company, Radius Choice ICC15-XLIS-RC), Principal (Principal Life Insurance Company, Income Protector ICC22-800-IDI), and The Standard (Standard Insurance Company, Platinum Advantage B180(7/17)). Lloyd’s of London, placed through Petersen International Underwriters, adds supplemental excess coverage above what the five carriers issue individually.
No carrier guide names “Quantitative Analyst” as a distinct occupation title. A quant is instead underwritten under the nearest cross-reference, most commonly Statistician, Data Scientist, or Financial Analyst; a Chartered Financial Analyst designation or Global Association of Risk Professionals certification can strengthen the file without changing that title question. The policy pays independently of Social Security Disability Insurance and is not key person disability insurance, which protects a firm’s balance sheet, not the quant’s own income. The occupation-class question below carries a close parallel on disability insurance for portfolio managers, the adjacent seat quants work beside on most trading desks.
Why Quantitative Analysts Face Distinctive Disability Risk
A quantitative analyst’s disability risk is financial, not physical, and it is built on a capacity a disability insurance application cannot easily verify, sustained, error-free quantitative reasoning under time pressure. A group long-term disability plan calculated on base salary alone insures the smallest share of a quant’s income, not the largest. Base salary at most banks, hedge funds, and trading firms moves slowly and predictably, set within a narrow band by seniority and desk. The bonus tied to a strategy’s realized performance, a model’s live results, or a desk’s overall trading outcome moves on an entirely separate track, and that track grows into a larger share of total pay the longer a quant’s models keep working.
A standard employer group long-term disability plan defines covered monthly earnings as base salary only, even when a year-end bonus, a deferred-compensation award, or restricted stock units tied to desk performance are reported on the identical W-2. Deferred compensation in particular creates a form of golden handcuffs, income already earned but not yet paid, that a group plan’s covered-earnings definition ignores entirely and that a disability can strand unvested.
The mechanism itself is not unique to quantitative work. It runs across disability insurance for financial services executives broadly, wherever incentive-linked pay outgrows a fixed base salary. Base salary rises roughly 3 to 3.5 percent a year across financial services broadly, a slow, predictable climb, while incentive-linked pay moves on a steeper, less predictable curve tied to performance. Quantitative analysts share this structure with disability insurance for investment bankers, though a quant’s bonus tracks a strategy’s statistical edge rather than deal flow. What is distinctive at the quant level is the analytical, cognitive nature of the work itself. A quant who loses the sustained mental focus a model demands, whether from a neurological event or an exhausting, high-pressure desk, can lose the ability to do the job without a single physical symptom a standard disability definition was written to recognize.
How the Five Carriers Deliver Own-Occupation Disability Insurance for Quantitative Analysts
This section is written for a quantitative analyst evaluating coverage before a disability happens, not a claimant appealing a denial after one. What follows describes how to buy the definition correctly the first time.
Own-occupation disability insurance pays a benefit when a quantitative analyst cannot perform the material and substantial duties of their specific occupation, even while working in a different one. A comparison job under an any-occupation test, the standard most group plans switch to, rarely calls on a quant’s own statistical or trading judgment and pays less. A neurological event that impairs sustained analytical focus is evaluated under the same own-occupation terms as any other physical disability, never capped the way a psychological diagnosis can be.
The five carriers do not deliver true own-occupation the same way. Two quotes carrying an identical monthly benefit and premium can be structurally different policies, and comparing quotes across all five carriers is the fastest way to see where each one stands before applying.
Own Occupation Definition by Carrier for Quantitative Analysts
 |
Ameritas Life Insurance Corp. 4501NC |
Guardian Berkshire Life Insurance Co. of America ICC16 18ID, Provider Choice |
MassMutual Massachusetts Mutual Life Insurance Co. ICC15-XLIS-RC, Radius Choice |
Principal Principal Life Insurance Company ICC22-800-IDI, Income Protector |
The Standard Standard Insurance Company B180(7/17), Platinum Advantage |
|---|---|---|---|---|---|
| How own occupation coverage is delivered | Base contract, choice of true or modified own occupation forms | Base contract, named choice of three definitions | Not in the base definition. A separately priced Own Occupation Rider | Built into the base definition | A separately priced Own Occupation Benefit Rider |
| The clause that changes the definition from true to modified own occupation | Modified form adds “and you are not working in any occupation for wage or profit” (specimen) | Modified form adds “and You are not Gainfully Employed” (specimen) | Own occupation only exists once the rider is elected and itemized on the policy specifications page (specimen) | No such clause. Working in another occupation does not end the benefit (specimen) | Modified form adds “you are not engaged in any other job or occupation for wage or profit” (specimen). The own occupation form drops this clause entirely |
| Total disability definition, verbatim from the specimen | “Totally Disabled means that, solely due to sickness or injury, you are not able to perform the material and substantial duties of your occupation.” | “Totally Disabled means that, solely due to Injury or Sickness, You are not able to perform the material and substantial duties of Your Occupation” (base Own Occupation choice; the modified choice adds the Gainfully Employed clause above) | Not published in the base definition. The rider supplies the own occupation standard once elected | “Totally Disabled even if You are Working in another occupation as long as You are unable to perform the Substantial and Material Duties of Your Own Occupation.” | Rider language supplies the own occupation standard once elected; the base modified-form definition is quoted in the row above |
| Applies to a quantitative analyst’s occupation class without a separate election | No carrier guide reviewed names “Quantitative Analyst” directly. Ameritas’s nearest cross-reference titles, Statistician and Data Scientist, reach occupation class 5A and up to 6A respectively (see the occupation class table below). The general own occupation definition applies uniformly regardless of which class is reached | No carrier guide reviewed names the title directly. Guardian’s nearest cross-reference titles, Statistician and Data Scientist, are both assigned Class 5 on Guardian’s own numeric scale. All three definition choices are available regardless of occupation class | No, on two counts. MassMutual does not name the title, and its nearest cross-reference title, Statistician, reaches 5A with no stated income floor, but the Own Occupation Rider must still be separately elected and priced regardless of which class is reached | No carrier guide reviewed names the title directly. Principal’s nearest cross-reference title, Data Scientist with a PhD, reaches Principal’s own top credentialed classification tier (see the occupation class table below); the built-in own occupation definition applies to every tier without election | No, on two counts. The Standard does not name the title, and its nearest cross-reference title, Data Scientist with a master’s degree or PhD, reaches 5A and qualifies for the carrier’s Preferred Occupation Discount; regardless of class, the Own Occupation Benefit Rider must still be separately elected and priced |
Source: specimen policy contracts held by Set for Life Insurance for Ameritas Life Insurance Corp. (form 4501NC), Berkshire Life Insurance Company of America underwriting for Guardian (form ICC16 18ID, Provider Choice), Massachusetts Mutual Life Insurance Company (form ICC15-XLIS-RC, Radius Choice), Principal Life Insurance Company (form ICC22-800-IDI, Income Protector), and Standard Insurance Company (form B180(7/17), Platinum Advantage). Quoted language is verbatim contract text. Guardian’s occupation class uses its own numeric scale, not a lettered class comparable to the others.
Who Should Consider Disability Insurance for Quantitative Analysts?
Quantitative work spans a wide income range across a single career, from a junior analyst building a first model to a senior researcher whose bonus dwarfs base salary. The right disability insurance depends on where a quant sits in that range and how compensation is currently structured.
Junior and Associate Quantitative Analysts Building a Model Track Record
A quant early in a career, still building the track record that eventually drives bonus income, qualifies for a lower occupation class and a smaller issue limit than a senior researcher’s, but locking in a policy while young and healthy secures the lowest available premium and preserves the option to raise coverage later through a Future Increase Option rider.
Quantitative Analysts With Bonus-Heavy or Deferred Compensation
A quant whose bonus or deferred compensation now outweighs base salary is the buyer for whom this page’s own-occupation and underwriting comparisons matter most. A carrier that delivers true own-occupation only through a rider adds a real premium line, and how that same carrier’s underwriting treats fluctuating bonus and deferred income directly affects the coverage amount a policy can be issued for.
Senior Quantitative Researchers at Peak Income
A senior quantitative researcher or desk head sits closest to a carrier’s top occupation class and its standard issue-and-participation limit, the exact income tier where base salary contributes the least to total compensation and a group plan’s base-salary-only definition leaves the most income uninsured. High-limit coverage above the standard-issue ceiling, placed through Lloyd’s of London, applies at this income level.
Quantitative Analysts Moving Between Buy Side and Sell Side
A quant moving from a sell-side bank’s trading desk to a buy-side hedge fund, or between two funds, loses employer group coverage the day employment ends, and a new employer’s group plan starts its own eligibility and pre-existing-condition clock. An individually owned policy stays in force through every one of those moves, since it belongs to the quant, not the desk.
Occupation Class and Underwriting for Quantitative Analysts
Occupation class is the underwriting tier a carrier assigns based on a quantitative analyst’s actual duties and documented income, not job title alone, and it sets the ceiling on the available monthly benefit. No carrier guide reviewed names Quantitative Analyst directly, so a quant is classified under the nearest title instead, most plausibly Statistician, Data Scientist, or Financial Analyst.
Which title lands the strongest class depends entirely on the carrier. At MassMutual, Statistician reaches a flat 5A while Market Research Analyst, describing the same underlying work, reaches only 3A. At Principal, Data Scientist with a PhD reaches the carrier’s top credentialed tier, higher than an Investment Analyst without that credential. The table below breaks out each carrier’s figures across all three titles.
Occupation Class by Carrier for the Titles Closest to a Quantitative Analyst
|
Ameritas Life Insurance Corp. |
Guardian Berkshire Life Insurance Co. of America |
MassMutual Massachusetts Mutual Life Insurance Co. |
Principal Principal Life Insurance Company |
The Standard Standard Insurance Company |
|---|---|---|---|---|---|
| Highest class reached under any of the three candidate titles below | 6A (via Data Scientist, earning more than $75,000 a year) | Class 5 (Guardian’s own numeric scale; not comparable to another carrier’s lettered class) | 5A (via Statistician, no stated income floor, or via CFA at more than $250,000 a year) | 5A-Select (via Data Scientist with a PhD, cross-referenced to Principal’s Executives classification) | 5A (via Data Scientist or Financial Analyst, both also eligible for the Preferred Occupation Discount) |
| Statistician | 5A. No income threshold stated in the section reviewed | Class 5. No income threshold stated in the section reviewed | 5A. No income threshold stated; the same class applies regardless of earnings | Not named in the guide on file | Not named in the guide on file |
| Data Scientist | Income-tiered: more than $75,000 a year reaches 6A; $75,000 a year or less reaches 5A | Class 5. No income threshold stated in the section reviewed | Not named in the guide on file | Data Scientist (PhD): “See Executives,” cross-referenced to Principal’s own top credentialed tier, 5A-Select on the Select product. No income threshold stated; the PhD is the qualifying credential | Data scientist (advanced data analytics) with a master’s degree or PhD: 5A, and eligible for the carrier’s 20% Preferred Occupation Discount. No specific income threshold stated beyond the credential requirement |
| Financial or Investment Analyst | Financial Analysts, grouped with Fund Managers, Portfolio Managers and Investment Bankers under Stocks and Securities: $150,000 a year for two years reaches 5A, others reach 4A. A separate, credential-based “Financial Analyst (non Stocks and Securities)” entry exists elsewhere in the guide: Certified reaches 6A, others reach 4A, with no income tier | Investment Analyst or Banker: Class 5, named directly on the Financial Underwriting eligible-occupations list. Section 9’s general requirements apply: a minimum of three years in the industry and three years of tax returns with supporting statements | Chartered Financial Analyst (CFA): income-tiered, more than $250,000 a year reaches 5A/5, down to 3A below $150,001 a year. A separately listed Market Research Analyst reaches only a flat 3A, two tiers below Statistician at the same carrier | Investment analyst and investment banking: $150,000 a year for two years reaches 5A, $75,000 to $149,999 a year for two years reaches 4A, below that reaches base class 3A | Financial Analyst, grouped with Broker, Hedge Fund Manager, Investment Banker and Stockbroker under the Bank, Credit Union, Finance, Savings and Loan, Title and Escrow section: $200,000 a year for each of the last two years reaches 5A and qualifies for the 20% Preferred Occupation Discount, $100,000 a year for each of the last two years reaches 4A, others reach 3A |
Source: producer-facing field underwriting and product guides held by Set for Life Insurance for Ameritas Life Insurance Corp., Berkshire Life Insurance Company of America underwriting for Guardian, Massachusetts Mutual Life Insurance Company, Principal Life Insurance Company, and Standard Insurance Company. These figures come from underwriting guidance, not policy contract language, so no policy form ID applies. None of the five guides names “Quantitative Analyst” directly; Statistician, Data Scientist, and Financial or Investment Analyst are the nearest cross-reference titles located this pass. Guardian’s occupation class uses its own numeric scale, not a lettered class comparable to the other carriers.
Elimination Period and Cost of Living Adjustment Options
The elimination period is the length of time a quantitative analyst must be disabled before benefit payments begin, and it varies by carrier. Ameritas offers the widest range, from 30 to 730 days, with the available options tied to the benefit period selected. Guardian offers 30 to 720 days, though its longest options carry state and benefit-period restrictions. Principal, The Standard, and MassMutual all offer a choice of 60, 90, 180, or 365 days. The Standard calls this provision a Benefit Waiting Period rather than an elimination period, a naming distinction required by California law but used company-wide in its own materials.
A Cost of Living Adjustment rider increases the monthly benefit each year a claim continues, keeping pace with inflation on a long-term disability. Guardian, Ameritas, Principal, and The Standard each let a buyer choose between a 3 percent and a 6 percent maximum annual increase, tied to the Consumer Price Index. MassMutual’s rider applies a fixed 3 percent compound increase with no higher option. Most carriers require a full year of disability before the adjustments begin.
Mental Health and Burnout Risk in a Demanding Analytical Role
The industry term mental and nervous applies exclusively to psychological diagnoses, depression, anxiety, addiction, and PTSD among them, never to neurological conditions. A stroke, a traumatic brain injury, or another neurological event that ends a quant’s ability to sustain the rigorous, error-free reasoning the job demands is covered under the same terms as any other physical disability, at full benefit, with no cap. This limitation covers only burnout, depression, and comparable psychological claims, a real risk in a role built on sustained analytical focus under constant market pressure.
Whether the limitation is mandatory or elective, and for how long, varies by carrier. Ameritas bakes a longer limitation into its higher occupation classes than its lower ones. The Standard makes it elective, with a discount, at the classes a quant is most likely to reach. Principal’s rider is a no-cost election regardless of class; MassMutual’s guide does not address the provision.
Mental and Nervous Disorder Benefit Limitation for Quantitative Analysts by Carrier
|
Ameritas Life Insurance Corp. Product Guide |
Guardian Berkshire Life Insurance Co. of America IDI Field Underwriting Guide |
Mass Mutual Massachusetts Mutual Life Insurance Co. Underwriting Guide |
Principal Principal Life Insurance Company Disability Product Guide |
The Standard Standard Insurance Company Product Guide |
|---|---|---|---|---|---|
| Mandatory or elective at the occupation classes a quantitative analyst typically reaches (5A, 6A) | Mandatory on the non-cancellable policy at classes 6A, 5A and 4A specifically | Mandatory on every package; the duration depends on which package tier is purchased, not on occupation class | Not addressed in the guide on file | Elective at every occupation class, no cost to add | Elective, with a discount, at classes 5A, 4A and 3A. Mandatory only for classes below 3A and for California policies |
| Duration if imposed or elected | 5-year cumulative limitation on the non-cancellable (NC) policy for non-medical classes 6A, 5A and 4A; 2 years for classes 3A and 2A on the same policy. A flat 2 years on the Guaranteed Renewable (GR) product regardless of class. No elective override documented in the guide on file | 12 months on the Essential package; a choice of 12 or 24 months on the Select package; a choice of 12, 24 months, or unlimited on the Premier package. A mandatory 24-month limitation overrides this choice in California and for a named list of medical specialties that does not include financial or analytical occupations | Not addressed in the guide on file; confirm directly with the carrier | 24-month lifetime benefit for mental and nervous or substance abuse claims when the no-cost MNSA rider is elected; without it, benefits are payable through the normal maximum benefit period | 24-month limitation by endorsement when elected at classes 5A, 4A and 3A; without it, benefits are payable through the full maximum benefit period. The same 24-month limitation is required, not elective, for classes 3D, 3P, 2A, 2P, A and B and for all California policies |
| Discount for accepting a limitation | Not applicable. The limitation is built into the base policy’s benefit schedule by occupation class, not elected, and no discount is stated in the guide on file | Discount scales with the duration elected: roughly 6 to 10 percent for a 24-month limitation up to 10 to 15 percent for a 6-month limitation, depending on the benefit period selected | Not addressed in the guide on file | Up to 10 percent. The MNSA rider itself carries no added cost | 10 percent premium rate discount when the 24-month limitation is elected |
Source: field underwriting and product guides published by Ameritas Life Insurance Corp., Berkshire Life Insurance Company of America (Guardian), Principal Life Insurance Company, and Standard Insurance Company. Massachusetts Mutual Life Insurance Company’s underwriting guide on file does not document mental and nervous disorder limitation terms; confirm directly with the carrier. State variations apply to every carrier’s provisions, and Guardian’s mandatory-limitation override list is built around specific medical specialties and California policies rather than financial or analytical occupations.
How Disability Carriers Calculate Residual Benefits for Bonus-Heavy Income
Residual disability coverage pays a partial benefit when a quantitative analyst loses income to a disability without becoming totally unable to work, a scenario a bonus-heavy career produces more often than an all-or-nothing claim. Because bonus and deferred-compensation income varies year to year, how each carrier calculates prior earnings before disability matters as much as the benefit formula itself, since two quants with an identical current-year loss can receive materially different residual checks depending on which prior-earnings window a carrier applies.
The table below covers five areas: the income-loss threshold, the benefit formula, whether residual can trigger without a prior total disability, the benefit period, and recovery-benefit provisions after returning to work. A sixth section on physician- and dentist-specific provisions does not apply to quantitative analysts and is not shown here.
How Disability Carriers Calculate Residual Benefits for Quantitative Analysts
|
Ameritas Life Insurance Corp. 4501NC · Enhanced Residual Rider (AERES) |
Guardian Berkshire Life Insurance Co. of America ICC16 18ID · Provider Choice + Enhanced Partial Rider |
Lloyd’s Petersen International Underwriters PDI111521 · Optional Residual Rider |
Mass Mutual Massachusetts Mutual Life Insurance Co. ICC15-XLIS-RC · Extended Partial Disability (EPR) |
Principal Principal Life Insurance Company ICC22-800-IDI · Income Protector |
The Standard Standard Insurance Company B180(7/17) · Platinum Advantage + Residual Riders |
|---|---|---|---|---|---|---|
| 1 · Income Loss Threshold That Triggers Residual Benefits | ||||||
| Minimum income loss required % of prior earnings that must be lost before residual benefits begin |
15% loss of monthly earnings (Specimen) One of the lowest thresholds available. Rider text states: loss must be “at least 15% of your prior monthly earnings” due to sickness or injury. |
Loss of Income due to disability (Specimen) Guardian’s Enhanced Partial rider defines “Loss of Income” as the difference between Prior Income and Current Income attributable solely to the Injury or Sickness. No explicit percentage floor in the base rider , benefit scales proportionally with income loss. Must be Gainfully Employed. |
Optional rider , threshold per rider terms (Specimen) Base Lloyd’s specimen (PDI111521) notes “Residual Disability is an optional benefit that only applies if the rider was purchased.” Rider text not included in this specimen. Typical Lloyd’s/PIU residual riders require income loss and inability to perform all material duties. |
20–80% loss of Predisability Earnings (Standard) EPR benefit is payable when Monthly Earnings fall to 20%–80% of Predisability Earnings. Below 20% earnings remaining triggers full benefit. Above 80% earnings remaining, no EPR benefit is paid. |
Loss of Earnings from own occupation (Specimen) Principal’s Residual Disability Benefit Rider requires a loss of Earnings due to Disability. The specimen confirms “Earnings” excludes unearned income. No explicit minimum percentage floor , benefit scales pro-rata with the earnings loss ratio. |
20% loss of Predisability Earnings (Enhanced); 15–20% for Short-Term version (Specimen) Specimen lists Basic, Enhanced, and Short-Term Residual riders. Enhanced Residual: benefit payable when Monthly Earnings are 20%–80% of Predisability Earnings. |
| 2 · Monthly Benefit Calculation Formula | ||||||
| Residual benefit formula How the monthly residual check is calculated |
Residual Monthly Benefit = (Loss of Monthly Earnings / Prior Monthly Earnings) x Base Monthly Benefit (Specimen) First 6 months minimum: The greater of (a) 50% of base monthly benefit OR (b) the formula result. 75%+ loss rule: If loss exceeds 75% of prior monthly earnings, treated as 100% loss and full base benefit is paid. Prior earnings: Average of highest 12-month or 24-month period before disability, indexed annually for CPI-U after year 1. |
Partial Disability Benefit = (Loss of Income / Prior Income) x Monthly Benefit (Specimen) Prior Income: Average monthly income for either (a) last 24 calendar months, or (b) the two calendar years with highest earnings in the three years before disability , whichever is greater. Current Income: All income for services during disability, excluding pre-disability earned-but-not-yet-received income. Full benefit floor: If loss of income is 100% or more of Prior Income, full monthly benefit is paid. |
Proportional formula , rider required (Specimen) Rider language not included in this specimen. Lloyd’s/PIU residual riders typically use a proportional income-loss formula: (income loss / pre-disability income) x base benefit. Confirm with current rider filing. |
EPR Benefit = [(Predisability Earnings – Monthly Earnings) / Predisability Earnings] x Monthly Benefit (Standard) Full benefit if earnings are less than 20% of predisability earnings. No benefit if earnings are greater than 80% of predisability earnings. Prior earnings: Average of the 24 months before disability began. |
Residual Benefit = (Loss of Earnings / Prior Earnings) x Maximum Monthly Benefit (Standard) Prior Earnings: Average monthly Earnings for the 12 months before disability. Current Earnings: Earnings during the disability period, excludes passive/unearned income. Minimum benefit: Typically 50% of base benefit for first 6 months. |
Residual Benefit = [(Predisability Earnings – Monthly Earnings) / Predisability Earnings] x Basic Monthly Benefit (Standard) Full benefit trigger: If Monthly Earnings are less than 20% of Predisability Earnings, full Basic Monthly Benefit is paid. Basic Residual Rider: Flat 50% of base benefit when qualifying criteria met. Enhanced Residual Rider: Proportional formula above; includes Recovery Benefit. |
| 3 · Prior Total Disability Requirement , Can Residual Trigger Independently? | ||||||
| Independent trigger Does residual require a prior period of total disability, or can it trigger on its own? |
Fully independent , no prior total disability required (Specimen) Ameritas AERES rider states benefits begin the later of: (1) the day after the end of the Elimination Period, OR (2) the day following a period of total disability for which benefits have been paid. Either path is valid. Days of both total and residual disability satisfy the elimination period. |
Fully independent , no prior total disability required (Specimen) Guardian’s Enhanced Partial Disability Benefit Rider uses its own Elimination/Accumulation Period. The insured must satisfy the Accumulation Period but does not need to first be Totally Disabled. Residual days count toward satisfying the Elimination Period. |
Rider-dependent , verify current rider (Specimen) Lloyd’s specimen confirms residual is an optional rider. The base policy elimination period can be satisfied by successive periods of Total Disability or Residual Disability, but rider must be reviewed for independence trigger language. |
Fully independent , no prior total disability required (Standard) MassMutual’s EPR rider allows residual disability claims to trigger directly after the elimination period without a prior total disability period. Both total and partial disability days satisfy the elimination period. |
Fully independent , no prior total disability required (Standard) Principal’s residual/partial disability rider triggers after the elimination period regardless of whether any total disability period occurred. The elimination period can be met by residual disability days alone. |
Fully independent , no prior total disability required (Standard) Standard’s Enhanced Residual Disability Benefit Rider triggers after the Benefit Waiting Period is satisfied, independent of any total disability. Days of Disability during the Benefit Waiting Period need not be consecutive. |
| 4 · Benefit Period for Residual Disability | ||||||
| Residual benefit period Maximum duration for which residual benefits can be paid |
Remaining unused portion of the Total Disability Maximum Benefit Period (Specimen) The Residual Maximum Benefit Period equals the total unused portion of the maximum benefit period for total disability shown on the schedule. Combined total and residual payments cannot exceed this period. Typically to Age 65/67 when selected. |
Same Benefit Period as Total Disability , to Age 65, 67, or 70 (Specimen) Benefit Periods of To Age 70/67/65 or 10/5/2 Years are available. The Enhanced Partial rider benefit period matches the policy benefit period. To Age 70 option available for physicians , distinctive among carriers. |
Per Schedule of Benefits / rider terms (Specimen) The residual rider benefit period is set at time of issue and shown on the Schedule of Benefits (Section 1-D). Confirm with current rider. |
To Age 65 (base); Extended to Age 65 via Maximum Benefit Period Endorsement (Specimen) Specimen shows coverage end date for Extended Partial Disability corresponding to the policy’s non-cancellable period to age 65. A separate Maximum Benefit Period Endorsement is available with its own premium schedule. |
Same as base policy Maximum Benefit Period , 2 years, 5 years, To Age 65/67/70 (Specimen) Options include To Age 65, 67, and 70. Residual benefits run within this same period. To Age 70 available depending on occupation class. |
Same as base policy Maximum Benefit Period , to Age 67 in this specimen (Specimen) Maximum Benefit Period schedule applies (e.g., if disability begins at 62: 60 months; at 63: 48 months). Enhanced Residual Disability Benefit Rider matches base benefit period. |
| 5 · Recovery Benefit Provisions | ||||||
| Recovery benefit Protections after returning to work , continued payments if income remains depressed |
Explicit Recovery Benefit provision (Specimen) Triggers after a disability benefit period ends if the insured has returned to work, is performing material duties 80% or more of prior time, and still has 15% or more loss of monthly earnings demonstrably caused by the prior disability. Duration: Continues up to the residual maximum benefit period. |
Recovery Benefit , income-loss based, ongoing (Specimen) Benefits continue post-recovery as long as Loss of Income persists due to the disability. Because Guardian uses an income-loss formula, benefits naturally continue as long as Current Income remains below Prior Income due to the disabling condition. Prior Income protection: Uses the best 24-month or best-2-of-3-years average. |
Recovery benefit per rider , verify current rider (Specimen) Lloyd’s base specimen does not contain recovery benefit language. Standard Lloyd’s/PIU residual riders may include recovery provisions, but this must be confirmed against the current executed rider. |
Recovery Benefit included in EPR rider (Standard) After returning to full-time work following a disability for which EPR benefits were paid, if Monthly Earnings remain below Predisability Earnings due to the disability, a proportional recovery benefit continues. Duration: up to the remaining Maximum Benefit Period. |
Recovery Benefit , proportional, ongoing post-return (Standard) Provides recovery benefits when an insured has returned to Full Time Work but Earnings remain below prior levels due to the disability. Benefit calculated using the same proportional formula. |
Recovery Benefit included , Enhanced Residual Rider only (Specimen) The Basic Residual Rider does not include the Recovery Benefit , the Enhanced version is required. The base policy confirms premiums are waived while Recovery Benefits are payable. Short-Term Residual Rider: does not include recovery benefit. |
Source: specimen policy contracts and riders held by Set for Life Insurance, Ameritas Life Insurance Corp. (form 4501NC, Enhanced Residual Rider, AERES), Berkshire Life Insurance Company of America underwriting for Guardian (form ICC16 18ID, Provider Choice, Enhanced Partial Disability Benefit Rider), Petersen International Underwriters for Lloyd’s of London (form PDI111521, Optional Residual Rider), Massachusetts Mutual Life Insurance Company (form ICC15-XLIS-RC, Radius Choice, Extended Partial Disability Rider, EPR), Principal Life Insurance Company (form ICC22-800-IDI, Income Protector), and Standard Insurance Company (form B180(7/17), Platinum Advantage, Enhanced Residual Disability Benefit Rider).
How Group Long-Term Disability Compares to an Individual Policy for Quantitative Analysts
A quantitative analyst already covered by an employer’s group long-term disability plan still needs individual disability insurance, because the two protect different things for bonus-heavy income. Group long-term disability narrows the own-occupation definition over time, caps the benefit at a flat dollar ceiling, and ends the moment employment does, since the Employee Retirement Income Security Act of 1974 makes it the employer’s plan, not the quant’s. An individual policy stays own-occupation for the full benefit period, sets its benefit by occupation class and income, including bonus and deferred-compensation pay a group plan excludes, and travels with the quant through every firm change.
Taxability compounds the shortfall for this audience. Under Internal Revenue Code Section 104(a)(3), a group long-term disability benefit is taxable to the employee whenever the employer paid the premium, the standard arrangement most financial services employers use. An individual policy, paid for with after-tax dollars, pays a tax-free benefit instead, a second, compounding shortfall stacked on top of the covered-earnings shortfall the table below documents.
Group Long-Term Disability Versus an Individual Policy
| What the coverage does | Group Long-Term Disability | Individual Disability Insurance |
|---|---|---|
| How long the own-occupation definition lasts | Usually converts to an any-occupation test after 24 months of disability | True own-occupation for the full benefit period, delivered in base contract language at some carriers and through a rider at others |
| What income the plan actually insures | Most plans define covered earnings as base salary and exclude incentive pay, bonuses, commissions, and in some cases stock compensation. A smaller number reach a broader figure closer to total cash compensation | Earned income at the time of application, evaluated against the carrier’s own issue-and-participation limits and income documentation requirements |
| How the maximum monthly benefit is set | A flat dollar ceiling built into the employer’s plan. Group LTD maximums examined for the Wall Street Income Protection Report ranged from $3,000 to $20,000 a month, unrelated to the insured’s occupation class or income growth after enrollment | An issue-and-participation limit tied to occupation class and income. Principal’s Income Protector (form ICC22-800-IDI) carries a $35,000 monthly issue limit for occupation classes 6A+ through 3A at ages 18 to 60 |
| Whether the benefit is taxable | Taxable to the employee under Internal Revenue Code Section 104(a)(3) when the employer pays the premium, the standard group arrangement | Tax-free when the insured pays the premium with after-tax dollars |
| What happens to coverage at a job change | Ends with employment. A new employer’s plan starts its own eligibility and pre-existing-condition clock | Stays in force regardless of employer. The policy belongs to the insured, not the job |
Source: the Set for Life Insurance Wall Street Income Protection Report (group LTD findings across contracts examined for that report, none from a financial services employer directly, all underwritten by carriers active in this sector); Principal Life Insurance Company’s Disability Product Guide, form ICC22-800-IDI, Income Protector; and Internal Revenue Code Section 104(a)(3). The individual-policy maximum monthly benefit shown is Principal’s own published limit, not a figure common to all five carriers SFL represents.
A Hypothetical Example
A quant earning $220,000 in base salary and $380,000 in year-end bonus, $600,000 total, is a realistic profile at the senior end of this field. A standard group disability plan replacing 60 percent of base salary alone would pay roughly $11,000 a month, insuring barely a third of this analyst’s actual income.
Figures are hypothetical and for illustration only. They are not a quote or a guarantee of coverage.
Disability Insurance for Quantitative Analysts FAQ
Sources and Industry References
Disability insurance for quantitative analysts draws on carrier specimen contracts, riders, field underwriting guides, federal statute, and the Set for Life Insurance Wall Street Income Protection Report.
- Ameritas Life Insurance Corp., Guardian underwritten by Berkshire Life Insurance Company of America, MassMutual, Principal Life Insurance Company, and Standard Insurance Company each supply the specimen policy contracts, riders, and field underwriting guides this page cites by form number.
- Lloyd’s of London, placed through Petersen International Underwriters, a licensed managing general agent, underwrites the excess disability coverage referenced above what the five standard-issue carriers write.
- The Set for Life Insurance Wall Street Income Protection Report supplies the group long-term disability findings cited for benefit caps, own-occupation duration, and taxability.
- Internal Revenue Code Section 104(a)(3) governs the taxability of a group long-term disability benefit paid on an employer-paid premium, cited above.
- The Employee Retirement Income Security Act of 1974 governs employer-sponsored group long-term disability plans and explains why individual coverage stays in force after a job change.
Disclaimer
The information on this page is for general informational purposes only and does not constitute legal, financial, or tax advice. Coverage availability, underwriting terms, and eligibility requirements vary by occupation, income structure, health history, and state of residence. Policy terms described on this page are drawn from specimen policy language and are subject to change. Actual policy terms govern in all cases.
Excess disability coverage above standard carrier issue limits is underwritten by certain underwriters at Lloyd’s of London and accessed through Petersen International Underwriters, a licensed managing general agent. Compensation figures and occupation-class examples referenced on this page are illustrative only. Set for Life Insurance is a licensed insurance producer.