Key Person Disability Insurance
Protects the business when a critical employee cannot work.
Disability Coverage for the Employee Your Business Depends On
Key person disability insurance pays the business, not the employee, when a critical owner or non-owner employee cannot work due to disability. Set for Life Insurance compares key person coverage from Guardian, Principal Financial Group, MassMutual, The Standard and Ameritas for businesses whose revenue concentrates in one person’s work. Coverage pairs with small business disability insurance and business overhead expense insurance to protect the full range of a small business’s disability exposure.
Get Your Customized Key Person Disability Quote
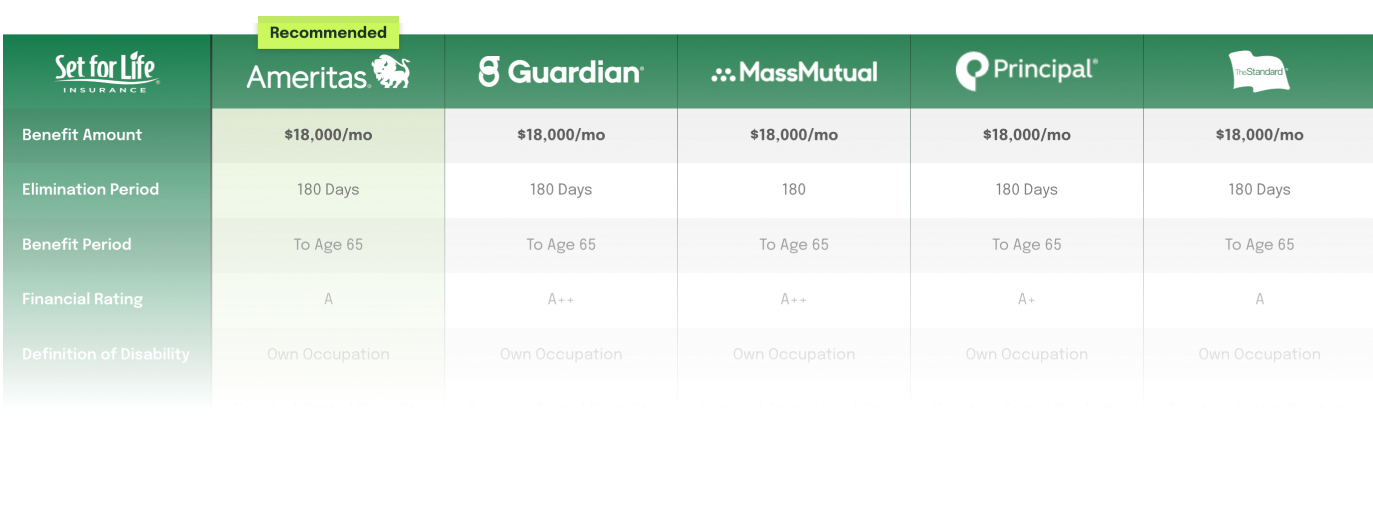
Compare Key Person Disability Insurance Quotes Side‑by‑Side
"*" indicates required fields
Key Person Disability Insurance
What BOE Covers
Key person disability insurance, also called key man disability insurance or key man insurance, pays the business a benefit when a key person, an owner or a critical non-owner employee, becomes disabled and cannot work. The business is the policy owner, the premium payer and the beneficiary. The key person is the insured, but never receives the benefit directly. This structure differs from personal individual disability insurance, which insures an individual’s own income and pays that individual.
Principal’s Key Person Replacement product defines the key person as an employee, owner or non-owner, whose loss of work materially affects the business, and requires a minimum earned income of $30,000 a year to qualify. The benefit replaces revenue that concentrates in one person’s work and funds the cost of recruiting, hiring and training a replacement during the disability.
Premium for key person disability insurance is not deductible as a business expense, because the policy is treated as a capital expenditure rather than an operating cost. Benefits paid to the business are generally received tax-free. This is the reverse of business overhead expense insurance, whose premium is deductible and whose benefit is taxable to the business. Owners should confirm current tax treatment with a tax advisor.
Coverage renews to a set age (age 65 under Principal’s design) and ends earlier if the key person stops actively working in the insured occupation for any reason other than the disability itself, if the business terminates the policy, or if the maximum benefit has been paid.
BOE Across the 5 Major Carriers
Guardian, Principal Financial Group, MassMutual, The Standard and Ameritas each write key person disability insurance, sometimes still marketed as key man disability insurance. Principal’s Key Person Replacement product (form HH772) is documented in detail below because its plan design, a choice between a lump-sum-only benefit and a combination of a monthly benefit plus a reduced lump sum, is well specified in its published product guide.
 |
Principal Key Person Replacement Form HH772 |
|---|---|
| Who is insured | An owner or non-owner employee earning $30,000 or more a year, critical to the business |
| Policy owner and beneficiary | The business |
| Occupation classes | 5A, 5A-M, 4A, 4A-M, 3A, 3A-M |
| Issue ages | 18 to 55 single-life; 18 to 60 multi-life (3 or more key person policies) |
| Payment methods | Lump sum only, or a combination of a monthly benefit and a reduced lump sum |
| Elimination periods, monthly benefit | 90 or 180 days |
| Elimination periods, lump sum | 180, 365 or 730 days |
| Lump-sum-only benefit calculation | Earned income times four, up to $1,000,000, minimum $5,000 |
| Combination benefit calculation | Monthly benefit capped at $20,000 using the individual DI issue-and-participation table; lump sum reduced by monthly benefits paid, combined total capped at $1,000,000, lump-sum portion alone capped at $500,000 |
| Minimum earned income to qualify | $30,000 a year |
| Renewal | Continuable to age 65 |
| Not available | California, Florida, Montana, New York, Vermont |
Guardian, MassMutual, The Standard and Ameritas also write key person disability insurance. Benefit-calculation formulas, elimination-period menus, occupation-class rules and state availability vary by carrier. Set for Life Insurance confirms current specifics for each carrier at quoting time rather than publishing figures that could be out of date by carrier or state.
Source: Principal Disability Product Guide, Section 10, Key Person Replacement (HH772). Benefit amounts shown are maximum issue limits under Principal’s published underwriting guidelines; actual amounts depend on documented earned income and underwriting.
Choosing the Right Benefit Period
Key person disability insurance can pay a single lump sum, or a combination of a monthly benefit followed by a reduced lump sum. The choice shapes how much cash the business receives and when.
A lump-sum-only benefit pays once, at the end of the elimination period, in an amount tied to the key person’s earned income. This suits a business that needs immediate capital to recruit and train a replacement or absorb a sudden revenue gap, rather than a stream of payments over time.
A combination benefit pays a smaller monthly amount first, then a reduced lump sum once the lump-sum elimination period is satisfied. This suits a business that expects an extended transition and wants ongoing cash flow during that window rather than one large payment up front. The monthly and lump-sum elimination periods can differ; the monthly elimination period must be shorter than the lump-sum elimination period so the monthly benefit bridges the gap.
A shorter elimination period raises the premium. The right structure depends on how quickly the business needs capital, how long a replacement takes to recruit and train, and whether the business prefers one payment or a bridge of monthly payments into a smaller lump sum.

She made updating my files with each life event stress-free. I watched colleagues struggle to communicate with insurance companies, but not me. One email to Jamie and everything is taken care of. My family is protected and done so with ease, all thanks to Jamie. I highly recommend Set For Life!!!
Who Should Consider BOE
Key person disability insurance applies to any business whose revenue, operations or client relationships concentrate in one person’s work. The four situations below describe the exposure rather than the entity type or industry.
Businesses Whose Revenue Concentrates in One Person
A rainmaker partner, a lead producer, a founder with the client relationships, or a specialist whose skills the business cannot easily replace all create the same exposure. If that person cannot work, revenue drops immediately and the business needs capital to find, hire and train a replacement while covering the gap.
Minority Owners and Non-Owner Key Employees
Key person coverage is not limited to majority owners. Principal’s own underwriting guidelines design the product for minority owners and non-owner employees earning $30,000 or more a year who are critical to the business, a top salesperson, a lead engineer, or an operations manager the business depends on.
Businesses Preparing for a Lender or Investor Review
Lenders and outside investors sometimes require key person coverage as a condition of financing or investment, since a lender’s own repayment expectation and an investor’s own return expectation both depend on the business continuing to operate normally if a critical person is sidelined.
Businesses That Already Carry BOE or Buy-Sell Coverage
Business overhead expense insurance covers fixed operating costs. Disability buy-sell insurance funds an ownership transition. Neither replaces revenue concentrated in one person’s work, the gap key person disability insurance is built to fill. Businesses with multiple owners or significant fixed costs typically need key person coverage alongside those two, not instead of them.
If you need to insure a partner’s ownership share instead of revenue tied to one person’s work, see disability insurance for business owners. If your exposure is fixed operating costs, see business overhead expense insurance.
Key Person Disability Insurance FAQ
Buy Key Person Disability Insurance
Set for Life Insurance compares key person disability coverage from Guardian, Principal Financial Group, MassMutual, The Standard and Ameritas for businesses whose revenue concentrates in one person’s work. Key person coverage works alongside small business disability insurance to address both the individual’s income side and the business’s revenue-concentration side of a key employee’s disability.