Disability Insurance for Securities Brokers
Income Protection for Securities Brokers
Securities Broker Disability Coverage & Income Protection
Coverage Built Around Commission-Based Income
Set for Life Insurance is an independent disability insurance brokerage, not a life insurance, estate-planning, or cash-value product. Individual disability insurance for securities brokers replaces income a base-salary-only group plan was never built to see. Commission income can be the majority or the entirety of a securities broker’s total pay, and it moves with client activity and market conditions rather than a fixed schedule. That income sits outside what a brokerage firm’s group plan calculates its benefit from. Individual coverage is underwritten to income actually earned rather than a flat plan ceiling, insuring the share of compensation the group plan leaves out.
Compare Carriers for Securities Brokers
Individual Disability Insurance for Stockbrokers
"*" indicates required fields
Securities Broker Disability Insurance, Compared
What Individual Disability Insurance Covers for Securities Brokers
This page is for a securities broker or registered representative shopping for individual disability coverage, not for insurance agents or brokers looking to sell a disability policy. A securities broker in this context means a FINRA-registered representative of a broker-dealer, licensed under the Series 7 exam or its equivalent, whose own income, not a firm’s balance sheet, is what this coverage protects.
Individual disability insurance for securities brokers, sometimes called income protection, replaces income when a stockbroker or registered representative cannot perform the material and substantial duties of the occupation. It is structured separately from any group long-term disability plan a wirehouse or broker-dealer provides, and it stays in force through a firm change or a shift from commission-based to fee-based compensation. Coverage is non-cancellable and guaranteed renewable to a stated age, so the carrier cannot cancel the policy or raise the premium.
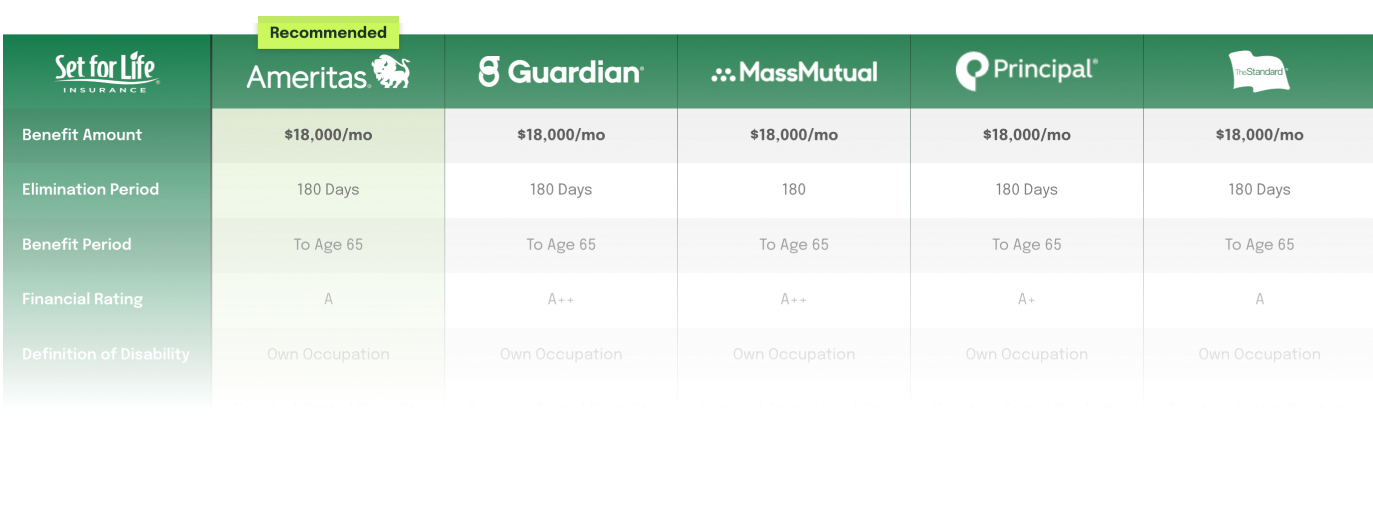
Five carriers underwrite the disability insurance securities brokers buy individually. Ameritas (Ameritas Life Insurance Corp., policy form 4501NC), Guardian (Berkshire Life Insurance Company of America, policy form ICC16 18ID Provider Choice), MassMutual (Massachusetts Mutual Life Insurance Company, Radius Choice ICC15-XLIS-RC), Principal (Principal Life Insurance Company, Income Protector ICC22-800-IDI), and The Standard (Standard Insurance Company, Platinum Advantage B180(7/17)). The policy forms listed here can be read in full among the sample individual disability insurance policies. Lloyd’s of London, placed through Petersen International Underwriters, adds supplemental excess coverage above what the five carriers issue individually.
The occupation-class and own-occupation questions below narrow the same cross-sector disability insurance for financial services executives framework to the specific title, income structure, and licensing context of a securities broker. Brokers in New York can also work with the Set for Life Insurance New York office.
Why Securities Brokers Face Distinctive Disability Risk
Group long-term disability coverage through a broker-dealer or wirehouse calculates its benefit from base salary alone in the plan documents examined for this comparison. Commission income, whether earned on trade execution, product sales, or an asset-based fee tied to assets under management, can be the majority or the entirety of a securities broker’s total pay, and it moves with client activity and market conditions rather than on a fixed schedule. A standard group plan’s covered-earnings definition was never built to see it.
A related employer-level census found that only 1.3 percent of financial-services employers carrying group long-term disability coverage also provide an individual or multi-life layer above it, a shortfall spanning banks, broker-dealers, and asset managers alike. For a securities broker whose compensation runs heavily on commission or a book of business built over a career, that shortfall between what the group plan replaces and what the broker actually earns is where an individually owned policy does its work. Disability insurance for investment bankers works through the identical shortfall from a deal-driven angle instead of a commission-driven one.
Income documentation carries its own commission-specific rule at underwriting. The Standard’s own instruction for a non-owner employee’s insurable income is to project current annual salary and add year-to-date commission and bonus already earned and paid, not to project commissions or bonuses forward. Ameritas requires 2 years of financial documentation for stock brokers, traders, and several other financial-industry occupations before issuing a policy. A carrier insures commission income a securities broker has already earned, W-2 compensation and 1099 commission income alike, not commission a broker expects to earn.
Some independent broker-dealer representatives already have access to a combined group and individual disability plan through FSI membership. Even where that coverage exists, it’s worth confirming how it defines total disability, how long it pays, and whether it moves with you if you change firms, the same questions worth asking about any employer or association-sponsored plan before deciding individual coverage on top of it isn’t needed.
Own Occupation Disability Insurance for Stockbrokers Across Five Carriers
Own-occupation coverage pays the full disability benefit when a securities broker cannot perform the material and substantial duties of the occupation, even while working in a different job entirely. How each carrier delivers that standard changes both the premium and the steps required at application. Guardian delivers 3 separate definitions in the base contract, letting a securities broker select the strength of the standard rather than paying extra for one.
Own Occupation Definition by Carrier for Securities Brokers
 |
Ameritas Life Insurance Corp. 4501NC |
Guardian Berkshire Life Insurance Co. of America ICC16 18ID, Provider Choice |
MassMutual Massachusetts Mutual Life Insurance Co. ICC15-XLIS-RC, Radius Choice |
Principal Principal Life Insurance Company ICC22-800-IDI, Income Protector |
The Standard Standard Insurance Company B180(7/17), Platinum Advantage |
|---|---|---|---|---|---|
| How own occupation coverage is delivered | Base contract, choice of true or modified own occupation forms | Base contract, named choice of three definitions | Not in the base definition. A separately priced Own Occupation Rider | Built into the base definition | A separately priced Own Occupation Benefit Rider |
| The clause that changes the definition from true to modified own occupation | Modified form adds “and you are not working in any occupation for wage or profit” (specimen) | Modified form adds “and You are not Gainfully Employed” (specimen) | Own occupation only exists once the rider is elected and itemized on the policy specifications page (specimen) | No such clause. Working in another occupation does not end the benefit (specimen) | Modified form adds “you are not engaged in any other job or occupation for wage or profit” (specimen). The own occupation form drops this clause entirely |
| Total disability definition, verbatim from the specimen | “Totally Disabled means that, solely due to sickness or injury, you are not able to perform the material and substantial duties of your occupation.” | “Totally Disabled means that, solely due to Injury or Sickness, You are not able to perform the material and substantial duties of Your Occupation” (base Own Occupation choice; the modified choice adds the Gainfully Employed clause above) | Not published in the base definition. The rider supplies the own occupation standard once elected | “Totally Disabled even if You are Working in another occupation as long as You are unable to perform the Substantial and Material Duties of Your Own Occupation.” | Rider language supplies the own occupation standard once elected; the base modified-form definition is quoted in the row above |
| Does reaching a higher occupation class remove the rider requirement | No separate rider to remove; the guide names “Brokers/Traders (bond, stock, commodity)” directly, reaching class 5A at $150,000/yr for 2 years, with a general “Others” tier at 4A. The own occupation choice of forms applies uniformly at either tier | No separate rider to remove; Guardian names “Broker – Stocks or Bonds (office duties only, not exchange floor)” directly at a flat Class 4 with no published income-tiered path to a higher class. All three definition choices are available regardless of class | Yes, still required, at every income tier. MassMutual’s “BROKER” entry (stock/bond/commodity broker or trader) runs four published tiers from a $250,000+/yr, 3-year, 5-year-tenure top tier down to an “All others” base tier. The Own Occupation Rider requirement applies uniformly across all four tiers | No separate rider to remove; Principal names “Stockbroker” directly, reaching 5A at $150,000/yr for 2 years with 5 years in business, with a 4A tier at $75,000/yr and a 3A base tier. The built-in own occupation definition applies to all three tiers without election | Yes, still required, at every income tier. The Standard groups Broker and Stockbroker inside its Bank, Credit Union, Finance bucket, reaching 5A at $200,000+/yr for 2 years (eligible for the Preferred Occupation Discount), with a 4A tier at $100,000+/yr and a 3A base tier. The Own Occupation Benefit Rider requirement applies at every tier, including the discount-eligible top tier |
Source: specimen policy contracts held by Set for Life Insurance for Ameritas Life Insurance Corp. (form 4501NC), Berkshire Life Insurance Company of America underwriting for Guardian (form ICC16 18ID, Provider Choice), Massachusetts Mutual Life Insurance Company (form ICC15-XLIS-RC, Radius Choice), Principal Life Insurance Company (form ICC22-800-IDI, Income Protector), and Standard Insurance Company (form B180(7/17), Platinum Advantage). The occupation-class figures in the fourth row are sourced separately from each carrier’s underwriting guide, not the policy contract. Lloyd’s of London coverage, placed through Petersen International Underwriters, is excess coverage and is not included in this comparison.
The rider requirement above lands hardest at MassMutual and The Standard, applying at every published income tier. A securities broker weighing those carriers against Ameritas or Principal, where the strongest definition ships in the base contract, is comparing a real premium line against a definition built in from the start.
Who Should Consider Income Protection for Securities Brokers
A securities brokerage career spans a wide income range, from a newly registered representative building a client base to a senior producer whose trailing commissions and book of business dwarf any base salary. The right disability insurance depends on where a securities broker sits in that range.
Newly Registered Representatives Building a Client Base
A securities broker early in a career, still building the client relationships and commissions that eventually drive income past base salary, qualifies for the base occupation class and a smaller issue limit. Locking in a non-cancellable policy while young and healthy secures the lowest premium and preserves the option to raise coverage later.
Securities Brokers With Established Commission-Based Income
A securities broker whose commission income has grown past the 2-year, mid-tier threshold most carriers publish is the buyer for whom this page’s own-occupation and occupation-class comparisons matter most. Whether the carrier still requires a separately priced Own Occupation Rider at this tier affects the premium and coverage amount.
Top-Producing Securities Brokers at Peak Income
A top-producing securities broker sits closest to a carrier’s highest occupation class and standard issue limit, the tier where a group plan’s base-salary-only definition leaves the largest share of income uninsured. High-limit coverage above the standard-issue ceiling, placed through Lloyd’s of London, applies here, and a residual benefit rider protects a partial loss of production.
Securities Brokers Changing Firms or Broker-Dealers
A securities broker moving a book of business from one broker-dealer to another, or from a wirehouse to an independent firm, loses employer group coverage the day employment ends. An individually owned policy stays in force through every one of those moves, since the policy belongs to the broker, not the desk.
Occupation Class Securities Brokers Reach at Each Carrier
Occupation class sets the ceiling on how much coverage a securities broker can be issued, and it moves with income and tenure differently at each of the five carriers. The income and tenure bar required to reach the top class ranges from a 2-year track record at Ameritas and Principal to a 5-year minimum tenure requirement layered on top of a 3-year income bar at MassMutual.
Occupation Class for Securities Brokers by Carrier
|
Ameritas | Guardian | MassMutual | Principal | The Standard |
|---|---|---|---|---|---|
| Top class reachable for an office-duties securities broker | 5A | Class 4 (flat, no income-tiered path) | 5A/5 | 5A | 5A (20% Preferred Occupation Discount eligible) |
| Income and tenure required to reach the top class | $150,000/yr for at least 2 years | No published income threshold; Class 4 is a flat assignment for office-duties stock or bond brokers | $250,000+/yr for at least 3 years, plus a minimum of 5 years in the business, not managing own account | $150,000/yr for at least 2 years, minimum 5 years in business | $200,000+/yr for each of the last 2 years |
| Middle tier, where a separate one is published | Not published; only a top tier and a general “Others” tier exist | Not applicable; a single flat class covers this title | Two middle tiers: $200,001 to $250,000/yr for 2 years reaches 5A; $150,000 to $200,000/yr for 2 years reaches 4A | $75,000/yr for at least 2 years, minimum 5 years in business, reaches 4A | $100,000+/yr for each of the last 2 years reaches 4A |
| Base or lowest tier if the income threshold is not met | 4A (“Others”) | Not applicable; the flat Class 4 applies regardless of income | 3A (“All others”) | 3A (base occupation class) | 3A (“Others”) |
| How the carrier names the title | “Brokers/Traders (bond, stock, commodity),” grouped with Fund Managers, Portfolio Managers, Financial Analysts, and Investment Bankers under Stocks and Securities | “Financial Industry – Broker – Stocks or Bonds (office duties only, not exchange floor),” with a separate “Stocks Brokers” entry among its general financial-industry eligibility list | “BROKER: Stock/bond/commodity broker or trader, investment or mortgage broker,” cross-referenced directly from a “STOCK BROKER” alphabetized entry | “Stockbroker,” cross-referenced from a “Stocks/bonds (not on floor of exchange)” entry under Sales occupations | “Broker” and “Stockbroker,” both named inside the Bank, Credit Union, Finance, Savings and Loan, Title and Escrow classification bucket |
Source: producer-facing field underwriting and product guides held by Set for Life Insurance for Ameritas Life Insurance Corp., Berkshire Life Insurance Company of America underwriting for Guardian, Massachusetts Mutual Life Insurance Company, Principal Life Insurance Company, and Standard Insurance Company. These figures come from underwriting guidance, not policy contract language, so no policy form ID applies to this table. Guardian’s occupation class is stated on its own numeric scale; a separate, narrower Guardian program chart (High Indemnity Program, PayGuard Plus) assigns a securities broker a different class, Class 3, for that add-on program’s own eligibility purposes only, and is not the general Class 4 shown here. All five carriers exclude exchange-floor trading and, at most carriers, day trading or trading primarily for one’s own account, from standard coverage under this title. Class assignment is subject to underwriter review at the time of application.
Elimination Period and Cost of Living Adjustment Options
The elimination period is the length of time a securities broker must be disabled before benefit payments begin, and it varies by carrier. Ameritas offers the widest range, from 30 to 730 days, with the available options tied to the benefit period selected. Guardian offers 30 to 720 days, though its longest options carry state and benefit-period restrictions. Principal, The Standard, and MassMutual all offer a choice of 60, 90, 180, or 365 days. The Standard calls this provision a Benefit Waiting Period rather than an elimination period, a naming distinction required by California law but used company-wide in its own materials.
A Cost of Living Adjustment rider increases the monthly benefit each year a claim continues, keeping pace with inflation on a long-term disability. Guardian, Ameritas, Principal, and The Standard each let a buyer choose between a 3 percent and a 6 percent maximum annual increase, tied to the Consumer Price Index. MassMutual’s rider applies a fixed 3 percent compound increase with no higher option. Most carriers require a full year of disability before the adjustments begin.
Mental Health and Burnout Risk for Securities Brokers
The industry term mental and nervous applies exclusively to psychological diagnoses, depression, anxiety, addiction, and PTSD among them, never to neurological conditions. A stroke, a traumatic brain injury, or another neurological event that ends a securities broker’s ability to maintain an active book of business is covered under the same terms as any other physical disability, at full benefit, with no cap. This limitation covers only burnout, depression, and comparable psychological claims, a real risk in a high-stress, client-facing, commission-driven role.
Whether the limitation is mandatory or elective, and for how long, varies by carrier. Ameritas bakes a longer limitation into its higher occupation classes than its lower ones. The Standard makes it elective, with a discount, at the classes a securities broker is most likely to reach. Principal’s rider is a no-cost election regardless of class; MassMutual’s guide does not address the provision.
Mental and Nervous Disorder Benefit Limitation for Securities Brokers by Carrier
|
Ameritas Life Insurance Corp. Product Guide |
Guardian Berkshire Life Insurance Co. of America IDI Field Underwriting Guide |
Mass Mutual Massachusetts Mutual Life Insurance Co. Underwriting Guide |
Principal Principal Life Insurance Company Disability Product Guide |
The Standard Standard Insurance Company Product Guide |
|---|---|---|---|---|---|
| Mandatory or elective at the occupation classes a securities broker typically reaches (5A, or a flat Class 4 at Guardian) | Mandatory on the non-cancellable policy at classes 6A, 5A and 4A specifically | Mandatory on every package; the duration depends on which package tier is purchased, not on occupation class | Not addressed in the guide on file | Elective at every occupation class, no cost to add | Elective, with a discount, at classes 5A, 4A and 3A. Mandatory only for classes below 3A and for California policies |
| Duration if imposed or elected | 5-year cumulative limitation on the non-cancellable (NC) policy for non-medical classes 6A, 5A and 4A; 2 years for classes 3A and 2A on the same policy. A flat 2 years on the Guaranteed Renewable (GR) product regardless of class. No elective override documented in the guide on file | 12 months on the Essential package; a choice of 12 or 24 months on the Select package; a choice of 12, 24 months, or unlimited on the Premier package. A mandatory 24-month limitation overrides this choice in California and for a named list of medical specialties that does not include financial or analytical occupations | Not addressed in the guide on file; confirm directly with the carrier | 24-month lifetime benefit for mental and nervous or substance abuse claims when the no-cost MNSA rider is elected; without it, benefits are payable through the normal maximum benefit period | 24-month limitation by endorsement when elected at classes 5A, 4A and 3A; without it, benefits are payable through the full maximum benefit period. The same 24-month limitation is required, not elective, for classes 3D, 3P, 2A, 2P, A and B and for all California policies |
| Discount for accepting a limitation | Not applicable. The limitation is built into the base policy’s benefit schedule by occupation class, not elected, and no discount is stated in the guide on file | Discount scales with the duration elected: roughly 6 to 10 percent for a 24-month limitation up to 10 to 15 percent for a 6-month limitation, depending on the benefit period selected | Not addressed in the guide on file | Up to 10 percent. The MNSA rider itself carries no added cost | 10 percent premium rate discount when the 24-month limitation is elected |
Source: field underwriting and product guides published by Ameritas Life Insurance Corp., Berkshire Life Insurance Company of America (Guardian), Principal Life Insurance Company, and Standard Insurance Company. Massachusetts Mutual Life Insurance Company’s underwriting guide on file does not document mental and nervous disorder limitation terms; confirm directly with the carrier. State variations apply to every carrier’s provisions, and Guardian’s mandatory-limitation override list is built around specific medical specialties and California policies rather than financial or analytical occupations.
How Disability Carriers Calculate Residual Benefits for Commission-Variable Income
Residual disability coverage pays a partial benefit when a securities broker loses income to a disability without becoming totally unable to work, a claim shape commission-based income produces more often than an all-or-nothing loss. How each carrier calculates prior earnings before disability matters as much as the benefit formula itself, since some carriers average the most recent 12 months and others average 24. A broker whose commissions dropped in the year before a claim is compared with a 12-month window at Principal and a 24-month window at MassMutual and The Standard.
The full residual benefit comparison on the financial services overview page covers the income-loss threshold, benefit formula, independent trigger, benefit period, and recovery benefit for all six carriers.
How Group Long-Term Disability Compares to an Individual Policy for Securities Brokers
Disability Insurance Securities Brokers Buy Individually, Outside the Firm’s Group Plan
A securities broker already covered by a broker-dealer’s group long-term disability plan still needs individual disability insurance, because the two protect different things for commission-heavy income. Group long-term disability narrows the own-occupation definition over time, caps the benefit at a flat dollar ceiling, and ends the moment employment does. An individual policy stays own-occupation for the full benefit period, sets its benefit by occupation class and income, including commission pay a group plan excludes, and travels with the broker through every firm change.
Taxability compounds the shortfall. Under Internal Revenue Code Section 104(a)(3), a group long-term disability benefit is taxable to the employee whenever the employer paid the premium, the standard arrangement most broker-dealers use. An individual policy, paid for with after-tax dollars, pays a tax-free benefit instead. The disability insurance securities brokers buy individually is the layer that follows the broker, not the firm. For the same comparison across other professions, see how individual coverage differs from a group plan.
Group Long-Term Disability Versus an Individual Policy
| What the coverage does | Group Long-Term Disability | Individual Disability Insurance |
|---|---|---|
| How long the own-occupation definition lasts | Usually converts to an any-occupation test after 24 months of disability | True own-occupation for the full benefit period, delivered in base contract language at some carriers and through a rider at others |
| What income the plan actually insures | Most plans define covered earnings as base salary and exclude incentive pay, bonuses, commissions, and in some cases stock compensation. A smaller number reach a broader figure closer to total cash compensation | Earned income at the time of application, evaluated against the carrier’s own issue-and-participation limits and income documentation requirements |
| How the maximum monthly benefit is set | A flat dollar ceiling built into the employer’s plan. Group LTD maximums examined for Disability Coverage Stops at Base Salary ranged from $3,000 to $20,000 a month, unrelated to the insured’s occupation class or income growth after enrollment | An issue-and-participation limit tied to occupation class and income. Principal’s Income Protector (form ICC22-800-IDI) carries a $35,000 monthly issue limit for occupation classes 6A+ through 3A at ages 18 to 60 |
| Whether the benefit is taxable | Taxable to the employee under Internal Revenue Code Section 104(a)(3) when the employer pays the premium, the standard group arrangement | Tax-free when the insured pays the premium with after-tax dollars |
| What happens to coverage at a job change | Ends with employment. A new employer’s plan starts its own eligibility and pre-existing-condition clock | Stays in force regardless of employer. The policy belongs to the insured, not the job |
Source: Disability Coverage Stops at Base Salary, the Set for Life Insurance 2026 report (group LTD findings across contracts examined for that report, underwritten by carriers active in this sector); Principal Life Insurance Company’s Disability Product Guide, form ICC22-800-IDI, Income Protector; and Internal Revenue Code Section 104(a)(3). The individual-policy maximum monthly benefit shown is Principal’s own published limit, not a figure common to all five carriers SFL represents.
Comparing coverage across the five carriers a securities broker qualifies for is easiest through side by side quotes for disability insurance rather than a single-carrier illustration.
A Hypothetical Example
Many securities brokers work as 1099 independent contractors rather than W-2 employees. A broker earning $180,000 in trailing twelve-month commission income may have no employer-sponsored group disability plan at all to fall back on, since group LTD is typically an employee benefit, not something extended to independent producers. For this segment, individual disability insurance is often not a supplement to group coverage. It is the only coverage.
Figures are hypothetical and for illustration only. They are not a quote or a guarantee of coverage.
Coverage for Independent Brokers and Their Offices
Securities Broker Business Overhead Coverage
An independent broker keeps paying office rent, assistant payroll and licensing fees during a disability. Overhead expense insurance reimburses those documented costs while the broker recovers.
Business Loan Protection for Broker-Dealers
A broker who bought a book of business or office space owes monthly installments. Loan protection keeps those payments current to the lender while the owner recovers from illness or injury.
Self-Employed Stockbroker Disability Insurance
Independent representatives are paid through commissions, with no employer plan behind the income. A self-employed policy provides a monthly benefit when illness or injury keeps them from clients.
Disability Insurance for Securities Brokers FAQ
Sources and Industry References
Disability insurance for securities brokers draws on carrier specimen contracts, riders, field underwriting guides, federal statute, and Disability Coverage Stops at Base Salary, the Set for Life Insurance 2026 report.
- Ameritas Life Insurance Corp., Guardian underwritten by Berkshire Life Insurance Company of America, MassMutual, Principal Life Insurance Company, and Standard Insurance Company each supply the specimen policy contracts, riders, and field underwriting guides this page cites by form number.
- Lloyd’s of London, placed through Petersen International Underwriters, a licensed managing general agent, underwrites the excess disability coverage referenced above what the five standard-issue carriers write.
- Disability Coverage Stops at Base Salary, the Set for Life Insurance 2026 report, supplies the group long-term disability findings cited for benefit caps, own-occupation duration, and taxability.
- Internal Revenue Code Section 104(a)(3) governs the taxability of a group long-term disability benefit paid on an employer-paid premium, cited above.
- The Employee Retirement Income Security Act of 1974 governs employer-sponsored group long-term disability plans and explains why individual coverage stays in force after a job change.
Last updated: November 16, 2026.
Disclaimer
The information on this page is for general informational purposes only and does not constitute legal, financial, or tax advice. Coverage availability, underwriting terms, and eligibility requirements vary by occupation, income structure, health history, and state of residence. Policy terms described on this page are drawn from specimen policy language and are subject to change. Actual policy terms govern in all cases.
Excess disability coverage above standard carrier issue limits is underwritten by certain underwriters at Lloyd’s of London and accessed through Petersen International Underwriters, a licensed managing general agent. Compensation figures and occupation-class examples referenced on this page are illustrative only. Set for Life Insurance is a licensed insurance producer.