Disability Insurance for Software Engineers
Income Protection for Software Engineers
Tech Worker Disability Coverage & Income Protection
Coverage Built Around Salary, Bonus, and Stock Pay
Individual disability insurance for software engineers replaces income that an employer’s group plan counts only as far as its covered-earnings clause allows. Salary, bonus and restricted stock units reach an engineer through different channels, and each plan decides which of them count. A personally owned, non-cancellable policy is underwritten to earned income and stays with the engineer through every job change.
Compare Carriers for Software Engineers
Income Protection for Software Engineers
"*" indicates required fields
Software Engineer Disability Insurance, Compared
What Individual Disability Insurance Covers for Software Engineers
This page is for a software engineer buying individual disability insurance before a disability happens, not one appealing a denied claim. It covers the buying decision only, not how to file, prove or appeal a claim afterward.
Individual disability insurance for software engineers, sometimes called income protection, is a personally owned policy that replaces income when an engineer cannot perform the material and substantial duties of their occupation. It is separate from any group long-term disability plan an employer provides, and it stays in force through a layoff, a resignation or a move to another company. Coverage is non-cancellable and guaranteed renewable to a stated age, so the carrier cannot cancel the policy or raise the premium while premiums are paid.
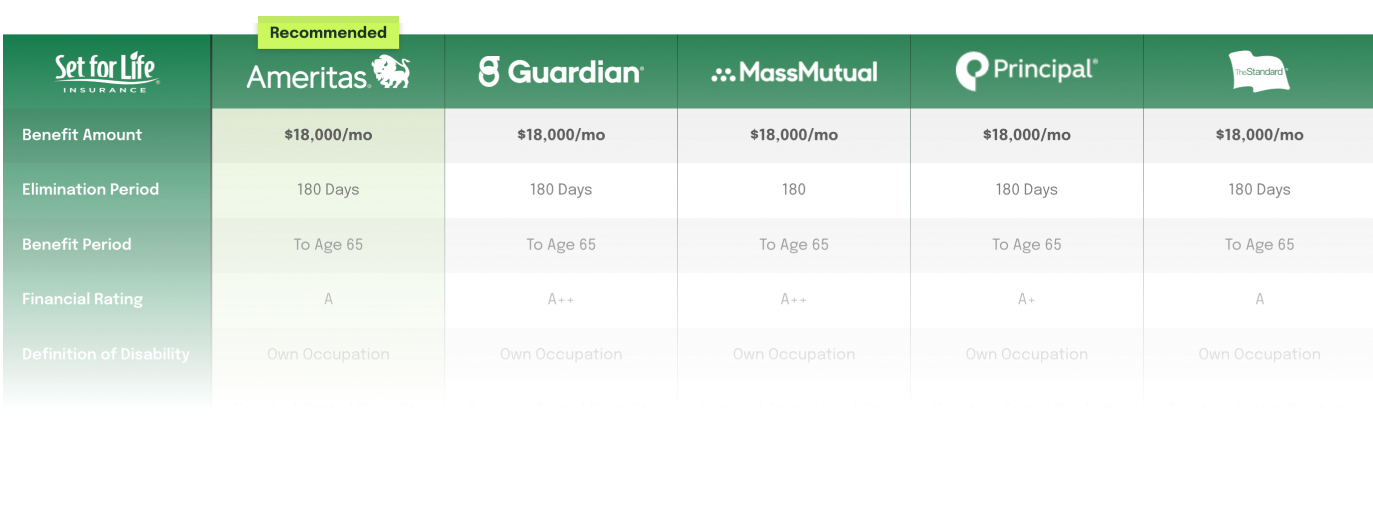
Five carriers write the individual policies this page compares. Ameritas (Ameritas Life Insurance Corp., policy form 4501NC), Guardian (Berkshire Life Insurance Company of America, policy form ICC16 18ID Provider Choice), MassMutual (Massachusetts Mutual Life Insurance Company, Radius Choice ICC15-XLIS-RC), Principal (Principal Life Insurance Company, Income Protector ICC22-800-IDI), and The Standard (Standard Insurance Company, Platinum Advantage B180(7/17)). Lloyd’s of London, placed through Petersen International Underwriters, adds excess coverage above what the five carriers issue individually.
The policy pays independently of Social Security Disability Insurance. It is also not key person disability insurance, which protects a company’s finances rather than the engineer’s own income.
Why Software Engineers Face Distinctive Disability Risk
The Social Security Administration’s Office of the Chief Actuary projects that an insured worker who attains age 20 in 2025 has a 24% probability, just under 1 in 4, of becoming disabled before normal retirement age (Actuarial Note 2025.6). A software engineer’s earning power rests on sustained concentration, vision and the use of the hands, and a condition that takes away any one of them can stop the work while the engineer is otherwise well.
The larger exposure is how the pay is built. An engineer’s compensation arrives as base salary, an annual bonus and restricted stock units that vest on a schedule. A group long-term disability plan pays a percentage of the earnings its covered-earnings clause names, and plans differ on whether that clause reaches bonus, commission or equity. Restricted stock units vest as shares rather than arriving in a paycheck, which leaves the plan document as the only place to learn whether they count.
Equity also ties an engineer to the employer. The group plan ends with the job, and a grant agreement decides what happens to unvested shares. An engineer who is ill, or who leaves because of a health condition, can lose the employer’s coverage and the unvested equity in the same month. An individual policy belongs to the engineer, so it is the one piece of protection that does not depend on staying employed.
How Insurers Count RSUs, Bonus and Salary for Software Engineers
The question that matters most to an engineer paid in stock is whether an individual carrier counts restricted stock units as insurable income. Two of the five carriers print a rule. Guardian (Berkshire Life Insurance Company of America) counts RSU compensation when it is a regular feature of income: earned for the last two years, expected to continue, with no change of employer or business in those two years. MassMutual (Massachusetts Mutual Life Insurance Company) counts RSUs that appear in W-2 wages as taxable income and averages them over two years, as the table below sets out, provided the employer’s plan has been in place at least three years.
Ameritas, Principal and The Standard print no RSU rule in the documents on file. That does not mean they exclude the income; it means an engineer whose pay is largely RSUs has to confirm the treatment with the carrier before applying. Salary and bonus have a printed rule at four of the five carriers, and the table shows each one.
The practical result is a different insurable income from the same W-2. At Guardian and MassMutual an engineer can document RSU income toward the benefit under the stated conditions, and at the other three carriers the treatment has to be confirmed before the RSU income can be counted on.
How Carriers Count Stock and Bonus Pay for Software Engineers
| What the carrier prints | Ameritas | Guardian (Berkshire Life) | MassMutual | Principal | The Standard |
|---|---|---|---|---|---|
| Restricted stock unit income | No RSU or stock rule is printed in the guide or the sample policy on file | RSU compensation counts as insurable income when it is a regular feature: earned for the last two years, expected to continue, with no change of employer or business during those two years | Counts RSUs included in W-2 wages as taxable income, using a two-year straight average. If current-year RSU income exceeds the prior year, the two years are averaged. If it is lower, 100% of the current year is used. If only the current year is provided, 75% of it is used. If no RSU income was received in the current year, none is added. The employer’s plan must have been in place at least three years, and the prior-year W-2 and a current-year paystub are required. The carrier may discontinue the program at any time. | No RSU or stock rule is printed in the guide | No RSU rule is printed in the guide. The sample policy (form B180(7/17)) counts stock options and stock bonuses as earnings at claim time when they pay for services in the insured’s profession; it does not name RSUs. |
| Bonus and variable pay | Fluctuating income over three years uses a weighted average. An income increase of 20% or more needs an explanation. Only tax-reported income counts, and higher future income is not projected for non-salaried applicants. | Bonus counts as insurable income under the same two-year regular-feature test | The underwriting guide on file prints no bonus rule | Bonus and commissions count as non-owner earned income. Falling income uses the lower, more recent year; rising or swinging income uses a three-year average. | The income figure is W-2 box 5, or projected salary plus year-to-date commission and bonus already paid. Bonuses are not projected, and two years of tax returns are required for bonus or commission income to be considered. |
Source: producer-facing field underwriting and product guides held by Set for Life Insurance for Ameritas Life Insurance Corp., Berkshire Life Insurance Company of America underwriting for Guardian (Field Underwriting Guide, Section 9), Massachusetts Mutual Life Insurance Company, Principal Life Insurance Company, and Standard Insurance Company, with the Standard sample policy (form B180(7/17)) and the MassMutual underwriting document “DI Underwriting – Restricted Stock Units” (form DI1604, dated 9/24). These figures come from underwriting guidance, not policy contract language, except where the cell names the sample policy. “No rule is printed” means the term was searched in the documents on file and not found; it does not mean the carrier excludes the income, and an engineer paid in RSUs should confirm treatment with the carrier before applying. Underwriting practice can go beyond the printed guides, and a carrier can change or withdraw a program at any time.
How the Five Carriers Deliver Own-Occupation Disability Insurance for Software Engineers
Own-occupation coverage pays when an insured cannot perform the material and substantial duties of their occupation, even if the insured is able to work in another one. Ameritas (policy form 4501NC) defines total disability this way: “Totally Disabled means that, solely due to sickness or injury, you are not able to perform the material and substantial duties of your occupation.”
The five carriers deliver this definition differently. Principal builds true own-occupation into the base contract at no added cost. Ameritas offers a true or a modified form in the base contract. Guardian offers a named choice of three definitions in the base contract. MassMutual and The Standard sell true own-occupation only through a separately priced rider, so skipping the rider at either carrier leaves a policy that pays a disability benefit without paying it on an own-occupation basis. Two quotes with the same benefit and the same premium can therefore describe different coverage.
For a software engineer the occupation is the work itself: writing, reviewing and designing software, which depends on sustained concentration, reading and keyboard use. A true own-occupation definition measures the claim against that work, so an engineer who cannot do it but can take a role outside engineering is still totally disabled. A modified definition adds a condition that the insured is not working in another occupation for wage or profit.
Who Should Consider Disability Insurance for Software Engineers?
Individual disability insurance fits a software engineer whose income depends on sustained technical work and whose employer coverage ends with the job or counts only part of the pay.
Engineers at Large Technology Employers
An engineer at a large technology employer holds a group long-term disability plan and a grant of restricted stock units that vests on a schedule. The group plan pays a percentage of what its covered-earnings clause names, and the clause decides whether bonus and stock count. An individual policy insures earned income as a carrier underwrites it, independent of the employer’s clause.
AI, Machine Learning and Data Science Engineers
Engineers who build models, training pipelines and data products work in roles where the title on the application drives the occupation class. A carrier classifies a data scientist, a machine learning engineer and a software engineer through its own title list, and the occupation class section below shows how each carrier lists them.
DevOps Engineers and UI/UX Designers
DevOps engineers, site reliability engineers and UI/UX designers share the screen-based, sustained-focus work of a software engineer, and each is classified by the title a carrier recognizes. An infrastructure engineer or a designer applies for the same individual coverage, underwritten to occupation class and documented income.
Engineers at Early-Stage Companies
An engineer at an early-stage company depends on a benefits package the company chose to buy and holds equity with no cash value until a sale or public offering. An individual policy does not depend on the employer’s plan and is underwritten on W-2 earnings. A carrier that counts stock income sets its own conditions, including how long the employer’s plan has existed.
Occupation Class and Underwriting for Software Engineers
Each carrier sorts occupations into classes, and the class is a main input to the limits and the premium that carrier quotes. No guide prints Software Engineer as a stand-alone title. Ameritas, Guardian and MassMutual print no software title and classify the nearest printed title, Systems Analyst or Programmer. Principal lists software developer inside a combined entry, and The Standard lists Software Developer, Senior Software Engineer and Software Architect inside a grouped entry.
The same engineer lands in different classes at different carriers, and each carrier’s class sits on its own scale. Each guide states that classification follows the actual duties and the underwriter’s judgment, not the title alone, so documenting the day-to-day work, the degree and the income matters as much as the title typed on the application. The table shows the title each guide prints, the class reached and what sets it.
Occupation Class by Carrier for Software Engineers
| What the guide prints | Ameritas | Guardian (Berkshire Life) | MassMutual | Principal | The Standard |
|---|---|---|---|---|---|
| Nearest printed title to software engineer or developer | Systems Analyst, Systems Engineer, Programmer. No Software Engineer or Software Developer title is printed. | Programmer and Computer Analyst. Systems Engineer and Design Engineer point to the Engineer entries. No Software Engineer or Software Developer title is printed. | Programmer and Systems Analyst. No Software Engineer or Software Developer title is printed. | One combined entry lists software developer, programmer, computer system analyst, database administration, information security analyst, computer network architect and network and computer systems administrator. | One grouped Computer Science/IT Professional entry lists Software Developer, Senior Software Engineer, Software Architect, Software Development Engineer, Programmer Analyst, Database Administrator, Network Engineer and System Administrator, among others. |
| Class reached and what sets it | 6A above $75,000 a year, 5A at $75,000 or less, 4A for others | Class 5 for Programmer and Computer Analyst. The printed Class 5 definition calls for at least $60,000 in salary including bonus for each of the past two years; Class 6 calls for $75,000. The guide does not say whether the listing depends on those tests. | Programmer is 5A in every column. Systems Analyst is 5A/5 in the Radius Choice column and 4A in the All Others column. No income floor is printed for either title. | 6A on Income Protector with earnings of at least $80,000 a year; 5A otherwise. The HH750-DI column prints 5A-Select and 5A. 6A is available in approved states. | 5A with a bachelor’s degree and earnings of $75,000 or more, 4A for others earning less than $75,000, 3A for earnings below $50,000 |
| Web developer | Not printed as a title | Not printed as a title | Web Developer/Engineer/Architect/Designer: 5A/5 in the Radius Choice column and 5A in the other three, contingent on a computer science degree or at least 5 years of experience | 4A, one tier below the software developer entry | Listed inside the grouped IT entry and takes its 5A, 4A and 3A lines |
| Data scientist | 6A above $75,000 a year, 5A at $75,000 or less | Data Scientist is Class 5. Data Engineer is Class 6 with a PE, PhD or master’s degree, Class 5 with a bachelor’s degree and Class 4 otherwise. | No Data Scientist title is printed. A bare Data row under the Scientist heading lists 5A/5 in the Radius Choice column and 5A in the others. | Data Scientist (PhD): See Executives on Income Protector, 5A-Select on HH750-DI. Computer and information research scientist: 6A. | Data scientist (advanced data analytics) with a four-year degree: 5A. A master’s degree or PhD makes the role eligible for the 20% Preferred Occupation Discount. |
| Graphic designer, the nearest printed title to UI/UX design | Graphic Designers: 5A with at least three years of experience and income above $75,000, 4A for others | Graphic Artist/Designer, office only, salaried: Class 4 | Graphic artist: 3A | Graphic designer: 4A | Graphic Designer is listed under Artist at 3A |
| W-2 engineer working from home | A DI underwriter reviews the case individually. Being a W-2 employee of a company is a printed favorable factor. | The guide does not address W-2 remote employees separately | Telecommuters who are W-2 employees need at least 30 hours per workweek and a W-2 or current paystub; coverage is available with no restrictions | W-2 employees of an outside firm will generally have no restrictions on coverage, according to the guide | W-2 employees may be eligible without modifications based on working-from-home status |
Source: producer-facing field underwriting and product guides held by Set for Life Insurance for Ameritas Life Insurance Corp. (Guide 3), Berkshire Life Insurance Company of America underwriting for Guardian (Field Underwriting Guide, October 2025), Massachusetts Mutual Life Insurance Company (Radius Choice column), Principal Life Insurance Company (Disability Product Guide), and Standard Insurance Company (Product Guide). These figures come from underwriting guidance, not policy contract language, so no policy form ID applies to this table. Each carrier’s class is stated on its own scale and is not equivalent to another carrier’s class; Guardian uses numbers and the other four use letters. None of the five guides prints AI Engineer, Machine Learning Engineer, DevOps Engineer or UI/UX Designer as a title; those roles are classified under the nearest printed title. Each guide states that classification follows actual duties and the underwriter’s judgment, not the title alone. Class assignment is subject to underwriter review at the time of application and varies by duties, employer, education and income documentation.
How Disability Carriers Calculate Residual Benefits for Software Engineers
Residual disability pays a partial benefit when an engineer can still work but earns less because of sickness or injury, such as reduced hours after a repetitive strain injury or a long treatment. The formula matters for an engineer paid in salary, bonus and equity, because each carrier sets its own income-loss threshold, its own benefit formula and its own definition of the prior earnings the loss is measured against. The table compares Ameritas, Guardian, Lloyd’s, MassMutual, Principal and The Standard on the loss threshold, the benefit formula, whether a prior total disability is required, the benefit period and the recovery benefit. It leaves out provisions that apply only to medical specialists.
Residual Disability Benefit Terms by Carrier for Software Engineers
 |
Ameritas Life Insurance Corp. 4501NC · Enhanced Residual Rider (AERES) |
Guardian Berkshire Life Insurance Co. of America ICC16 18ID · Provider Choice + Enhanced Partial Rider |
Lloyd’s Petersen International Underwriters PDI111521 · Optional Residual Rider |
Mass Mutual Massachusetts Mutual Life Insurance Co. ICC15-XLIS-RC · Extended Partial Disability (EPR) |
Principal Principal Life Insurance Company ICC22-800-IDI · Income Protector |
The Standard Standard Insurance Company B180(7/17) · Platinum Advantage + Residual Riders |
|---|---|---|---|---|---|---|
| 1 · Income Loss Threshold That Triggers Residual Benefits | ||||||
| Minimum income loss required % of prior earnings that must be lost before residual benefits begin |
15% loss of monthly earnings (Specimen) One of the lowest thresholds available. Rider text states: loss must be “at least 15% of your prior monthly earnings” due to sickness or injury. |
Loss of Income due to disability (Specimen) Guardian’s Enhanced Partial rider defines “Loss of Income” as the difference between Prior Income and Current Income attributable solely to the Injury or Sickness. No explicit percentage floor in the base rider; benefit scales proportionally with income loss. Must be Gainfully Employed. |
Optional rider: threshold per rider terms (Specimen) Base Lloyd’s specimen (PDI111521) notes “Residual Disability is an optional benefit that only applies if the rider was purchased.” Rider text not included in this specimen. Typical Lloyd’s/PIU residual riders require income loss and inability to perform all material duties. |
20 to 80% loss of Predisability Earnings (Standard) EPR benefit is payable when Monthly Earnings fall to 20% to 80% of Predisability Earnings. Below 20% earnings remaining triggers full benefit. Above 80% earnings remaining, no EPR benefit is paid. |
Loss of Earnings from own occupation (Specimen) Principal’s Residual Disability Benefit Rider requires a loss of Earnings due to Disability. The specimen confirms “Earnings” excludes unearned income. No explicit minimum percentage floor; benefit scales pro-rata with the earnings loss ratio. |
20% loss of Predisability Earnings (Enhanced); 15 to 20% for Short-Term version (Specimen) Specimen lists Basic, Enhanced, and Short-Term Residual riders. Enhanced Residual: benefit payable when Monthly Earnings are 20% to 80% of Predisability Earnings. |
| 2 · Monthly Benefit Calculation Formula | ||||||
| Residual benefit formula How the monthly residual check is calculated |
Residual Monthly Benefit = (Loss of Monthly Earnings / Prior Monthly Earnings) x Base Monthly Benefit (Specimen) First 6 months minimum: The greater of (a) 50% of base monthly benefit OR (b) the formula result. 75%+ loss rule: If loss exceeds 75% of prior monthly earnings, treated as 100% loss and full base benefit is paid. Prior earnings: Average of highest 12-month or 24-month period before disability, indexed annually for CPI-U after year 1. |
Partial Disability Benefit = (Loss of Income / Prior Income) x Monthly Benefit (Specimen) Prior Income: Average monthly income for either (a) last 24 calendar months, or (b) the two calendar years with highest earnings in the three years before disability, whichever is greater. Current Income: All income for services during disability, excluding pre-disability earned-but-not-yet-received income. Full benefit floor: If loss of income is 100% or more of Prior Income, full monthly benefit is paid. |
Proportional formula: rider required (Specimen) Rider language not included in this specimen. Lloyd’s/PIU residual riders typically use a proportional income-loss formula: (income loss / pre-disability income) x base benefit. Confirm with current rider filing. |
EPR Benefit = [(Predisability Earnings – Monthly Earnings) / Predisability Earnings] x Monthly Benefit (Standard) Full benefit if earnings are less than 20% of predisability earnings. No benefit if earnings are greater than 80% of predisability earnings. Prior earnings: Average of the 24 months before disability began. |
Residual Benefit = (Loss of Earnings / Prior Earnings) x Maximum Monthly Benefit (Standard) Prior Earnings: Average monthly Earnings for the 12 months before disability. Current Earnings: Earnings during the disability period, excludes passive/unearned income. Minimum benefit: Typically 50% of base benefit for first 6 months. |
Residual Benefit = [(Predisability Earnings – Monthly Earnings) / Predisability Earnings] x Basic Monthly Benefit (Standard) Full benefit trigger: If Monthly Earnings are less than 20% of Predisability Earnings, full Basic Monthly Benefit is paid. Basic Residual Rider: Flat 50% of base benefit when qualifying criteria met. Enhanced Residual Rider: Proportional formula above; includes Recovery Benefit. |
| 3 · Prior Total Disability Requirement: Can Residual Trigger Independently? | ||||||
| Independent trigger Does residual require a prior period of total disability, or can it trigger on its own? |
Fully independent: no prior total disability required (Specimen) Ameritas AERES rider states benefits begin the later of: (1) the day after the end of the Elimination Period, OR (2) the day following a period of total disability for which benefits have been paid. Either path is valid. Days of both total and residual disability satisfy the elimination period. |
Fully independent: no prior total disability required (Specimen) Guardian’s Enhanced Partial Disability Benefit Rider uses its own Elimination/Accumulation Period. The insured must satisfy the Accumulation Period but does not need to first be Totally Disabled. Residual days count toward satisfying the Elimination Period. |
Rider-dependent: verify current rider (Specimen) Lloyd’s specimen confirms residual is an optional rider. The base policy elimination period can be satisfied by successive periods of Total Disability or Residual Disability, but rider must be reviewed for independence trigger language. |
Fully independent: no prior total disability required (Standard) MassMutual’s EPR rider allows residual disability claims to trigger directly after the elimination period without a prior total disability period. Both total and partial disability days satisfy the elimination period. |
Fully independent: no prior total disability required (Standard) Principal’s residual/partial disability rider triggers after the elimination period regardless of whether any total disability period occurred. The elimination period can be met by residual disability days alone. |
Fully independent: no prior total disability required (Standard) Standard’s Enhanced Residual Disability Benefit Rider triggers after the Benefit Waiting Period is satisfied, independent of any total disability. Days of Disability during the Benefit Waiting Period need not be consecutive. |
| 4 · Benefit Period for Residual Disability | ||||||
| Residual benefit period Maximum duration for which residual benefits can be paid |
Remaining unused portion of the Total Disability Maximum Benefit Period (Specimen) The Residual Maximum Benefit Period equals the total unused portion of the maximum benefit period for total disability shown on the schedule. Combined total and residual payments cannot exceed this period. Typically to Age 65/67 when selected. |
Same Benefit Period as Total Disability: to Age 65, 67, or 70 (Specimen) Benefit Periods of To Age 70/67/65 or 10/5/2 Years are available. The Enhanced Partial rider benefit period matches the policy benefit period. |
Per Schedule of Benefits / rider terms (Specimen) The residual rider benefit period is set at time of issue and shown on the Schedule of Benefits (Section 1-D). Confirm with current rider. |
To Age 65 (base); Extended to Age 65 via Maximum Benefit Period Endorsement (Specimen) Specimen shows coverage end date for Extended Partial Disability corresponding to the policy’s non-cancellable period to age 65. A separate Maximum Benefit Period Endorsement is available with its own premium schedule. |
Same as base policy Maximum Benefit Period: 2 years, 5 years, To Age 65/67/70 (Specimen) Options include To Age 65, 67, and 70. Residual benefits run within this same period. To Age 70 available depending on occupation class. |
Same as base policy Maximum Benefit Period: to Age 67 in this specimen (Specimen) Maximum Benefit Period schedule applies (e.g., if disability begins at 62: 60 months; at 63: 48 months). Enhanced Residual Disability Benefit Rider matches base benefit period. |
| 5 · Recovery Benefit Provisions | ||||||
| Recovery benefit Protections after returning to work: continued payments if income remains depressed |
Explicit Recovery Benefit provision (Specimen) Triggers after a disability benefit period ends if the insured has returned to work, is performing material duties 80% or more of prior time, and still has 15% or more loss of monthly earnings demonstrably caused by the prior disability. Duration: Continues up to the residual maximum benefit period. |
Recovery Benefit: income-loss based, ongoing (Specimen) Benefits continue post-recovery as long as Loss of Income persists due to the disability. Because Guardian uses an income-loss formula, benefits naturally continue as long as Current Income remains below Prior Income due to the disabling condition. Prior Income protection: Uses the best 24-month or best-2-of-3-years average. |
Recovery benefit per rider: verify current rider (Specimen) Lloyd’s base specimen does not contain recovery benefit language. Standard Lloyd’s/PIU residual riders may include recovery provisions, but this must be confirmed against the current executed rider. |
Recovery Benefit included in EPR rider (Standard) After returning to full-time work following a disability for which EPR benefits were paid, if Monthly Earnings remain below Predisability Earnings due to the disability, a proportional recovery benefit continues. Duration: up to the remaining Maximum Benefit Period. |
Recovery Benefit: proportional, ongoing post-return (Standard) Provides recovery benefits when an insured has returned to Full Time Work but Earnings remain below prior levels due to the disability. Benefit calculated using the same proportional formula. |
Recovery Benefit included: Enhanced Residual Rider only (Specimen) The Basic Residual Rider does not include the Recovery Benefit: the Enhanced version is required. The base policy confirms premiums are waived while Recovery Benefits are payable. Short-Term Residual Rider: does not include recovery benefit. |
Source: specimen policy contracts and riders held by Set for Life Insurance: Ameritas Life Insurance Corp. (form 4501NC, Enhanced Residual Rider, AERES), Berkshire Life Insurance Company of America underwriting for Guardian (form ICC16 18ID, Provider Choice, Enhanced Partial Disability Benefit Rider), Lloyd’s of London through Petersen International Underwriters (form PDI111521), Massachusetts Mutual Life Insurance Company (form ICC15-XLIS-RC, Extended Partial Disability Rider), Principal Life Insurance Company (form ICC22-800-IDI, Income Protector) and Standard Insurance Company (form B180(7/17), Platinum Advantage with residual riders). Rider availability and terms vary by state and are subject to underwriter review at the time of application.
How Group Long-Term Disability Compares to an Individual Policy for Software Engineers
A group plan and an individual policy differ on five points: how long own-occupation coverage lasts, which income the plan insures, how the maximum monthly benefit is set, whether the benefit is taxable, and what happens at a job change. For a software engineer the second row decides the most, because the group plan’s covered-earnings clause determines whether bonus and stock count at all. An individual policy is underwritten to documented earned income, and the carriers’ own rules for stock and bonus income are in the table above.
Group Long-Term Disability Versus an Individual Policy
| What the coverage does | Group Long-Term Disability | Individual Disability Insurance |
|---|---|---|
| How long the own-occupation definition lasts | Usually converts to an any-occupation test after 24 months of disability | True own-occupation for the full benefit period, delivered in base contract language at some carriers and through a rider at others |
| What income the plan actually insures | Most plans define covered earnings as base salary and exclude incentive pay, bonuses, commissions, and in some cases stock compensation. A smaller number reach a broader figure closer to total cash compensation | Earned income at the time of application, evaluated against the carrier’s own issue-and-participation limits and income documentation requirements |
| How the maximum monthly benefit is set | A flat dollar ceiling built into the employer’s plan. Group LTD maximums examined for the Wall Street Income Protection Report ranged from $3,000 to $20,000 a month, unrelated to the insured’s occupation class or income growth after enrollment | An issue-and-participation limit tied to occupation class and income. Principal’s Income Protector (form ICC22-800-IDI) carries a $35,000 monthly issue limit for occupation classes 6A+ through 3A at ages 18 to 60 |
| Whether the benefit is taxable | Taxable to the employee under Internal Revenue Code Section 104(a)(3) when the employer pays the premium, the standard group arrangement | Tax-free when the insured pays the premium with after-tax dollars |
| What happens to coverage at a job change | Ends with employment. A new employer’s plan starts its own eligibility and pre-existing-condition clock | Stays in force regardless of employer. The policy belongs to the insured, not the job |
Source: the Set for Life Insurance Wall Street Income Protection Report, “How a group disability benefit is calculated,” “Own-occupation coverage is usually time-limited,” “The maximum monthly benefit binds first,” “Whether the benefit is taxed,” and “What happens to the coverage when you leave” (group LTD findings across contracts examined for that report, none from a financial services employer directly, all underwritten by carriers active in this sector); Principal Life Insurance Company’s Disability Product Guide, form ICC22-800-IDI, Income Protector (individual maximum monthly benefit example); and Internal Revenue Code Section 104(a)(3) (taxability). The individual-policy maximum monthly benefit shown is Principal’s own published limit and is not asserted as a figure common to all five carriers SFL represents. Group plan terms vary by employer and are shown as the common structure, not a specific plan’s terms. Terms shown are subject to the individual employer’s plan documents and underwriter review at the time of application.
Disability Insurance for Software Engineers FAQ
Sources and Industry References
Disability insurance for software engineers draws on carrier specimen contracts, riders, field underwriting guides, a carrier underwriting document on restricted stock units, federal statute, and the Set for Life Insurance Wall Street Income Protection Report.
- Ameritas Life Insurance Corp., Guardian underwritten by Berkshire Life Insurance Company of America, MassMutual, Principal Life Insurance Company, and Standard Insurance Company each supply the specimen policy contracts, riders and field underwriting guides this page cites by form number or guide section.
- Massachusetts Mutual Life Insurance Company supplies the underwriting document on restricted stock units (form DI1604) cited for how MassMutual counts RSU income.
- Lloyd’s of London, placed through Petersen International Underwriters, a licensed managing general agent, underwrites the excess disability coverage referenced above what the five standard-issue carriers write.
- The Social Security Administration’s Office of the Chief Actuary supplies the disability probability figure (Actuarial Note 2025.6, Table A).
- The Set for Life Insurance Wall Street Income Protection Report supplies the group long-term disability findings cited for benefit caps, own-occupation duration and taxability.
- Internal Revenue Code Section 104(a)(3) governs the taxability of a group long-term disability benefit paid on an employer-paid premium.
- The Employee Retirement Income Security Act of 1974 governs employer-sponsored group long-term disability plans and explains why individual coverage stays in force after a job change.
Disclaimer
The information on this page is for general informational purposes only and does not constitute legal, financial, or tax advice. Coverage availability, underwriting terms, and eligibility requirements vary by occupation, income structure, health history, and state of residence. Policy terms described on this page are drawn from specimen policy language and carrier underwriting guides and are subject to change. A carrier can change or withdraw an underwriting program at any time. Actual policy terms govern in all cases.
Excess disability coverage above standard carrier issue limits is underwritten by certain underwriters at Lloyd’s of London and accessed through Petersen International Underwriters, a licensed managing general agent. Compensation figures and occupation-class examples referenced on this page are illustrative only. Set for Life Insurance is a licensed insurance producer.