
Intern year starts the clock on resident disability insurance decisions, because it is the first year newly trained physicians earn income for clinical work. Any individual disability insurance for residents with an own-occupation definition is priced on the applicant’s age, health and occupation at application, and resident-only programs can end when training does. A resident who waits for a calmer year may find the easier route closed even though the work and the risk have not changed.
Interns enter this period with limited savings, significant student loan balances and little margin for income disruption. An illness or injury that interrupts work during intern year can have immediate financial consequences.
Resident-specific programs add a second deadline, because resident-only insurance eligibility can end at graduation for administrative reasons, not medical ones.
Andy Schafer, vice president of Workplace Benefits Solutions at Principal Financial Group, said in his podcast interview that the math rewards acting early.
“Purchasing protection when you’re 25 is much less expensive than it is when you’re purchasing it at 55 … As you become older, the chance that you become disabled, or the chance that you die, is much higher. The cost of insurance goes up as you age. So lock it in when you’re 25.”
Andy Schafer, vice president of Workplace Benefits Solutions at Principal Financial Group
Resident Disability Insurance Timing Throughout Training
During intern year, many residents can reach resident-specific programs designed for early training, including Residency Disability Insurance and Guaranteed Standard Issue (GSI) programs where an institution offers one.
Because premiums are based on age, a policy issued after training generally costs more, and an applicant whose health has changed may be offered different terms.
Age and health both work in an applicant’s favor early. Ethan F. Abramowitz, a disability insurance attorney at Seltzer & Associates, made the same point in his conversation on the podcast.
“The best time to get life insurance, the best time to get disability insurance, is when you’re young and healthy.”
Ethan F. Abramowitz, disability insurance attorney at Seltzer & Associates
Dr. Rodney Mogen, D.B.A., a brokerage director at MassMutual who trains financial advisers on disability insurance, said in an interview recorded for the podcast that he would rather get someone started on a small policy than leave them uninsured.
“I’d rather get someone started, even though it’s not necessarily going to solve all of their issues. But at least it gets them started, and then you can keep building on them from there.”
Dr. Rodney Mogen, D.B.A., brokerage director at MassMutual
Mogen said minimum benefits differ by carrier, generally about $500 a month, and recommended a policy with a future insurability option or a benefit increase rider so coverage can grow as income does.
Group Coverage Limits Versus Individual Disability Insurance for Residents
For many interns, hospital onboarding introduces disability coverage for the first time. Kurt Braundmeier, president of Baker Birdwell LLC, a disability-income-only firm, said in his podcast conversation that he enrolled in his own employer’s benefits without knowing what the coverage was.
“Checked that box whenever we were going through all of our benefits, but I wasn’t really sure of what disability insurance was.”
Kurt Braundmeier, president, Baker Birdwell LLC
Sean Eskra, a disability wholesaler and former group benefits representative at Principal Financial Group, said in his recorded interview that at the employers he served, with two to 1,000 employees, disability got less attention from HR staff than health coverage.
“the HR staff is so preoccupied with so many other moving pieces, especially in the medical world, … that the disability kind of goes to the wayside a little bit.”
Sean Eskra, disability wholesaler and former group benefits representative, Principal Financial Group
By the medical world, Eskra meant health plans, which he described as the revenue driver for many brokers. His observation comes from smaller employers and does not describe any particular hospital.
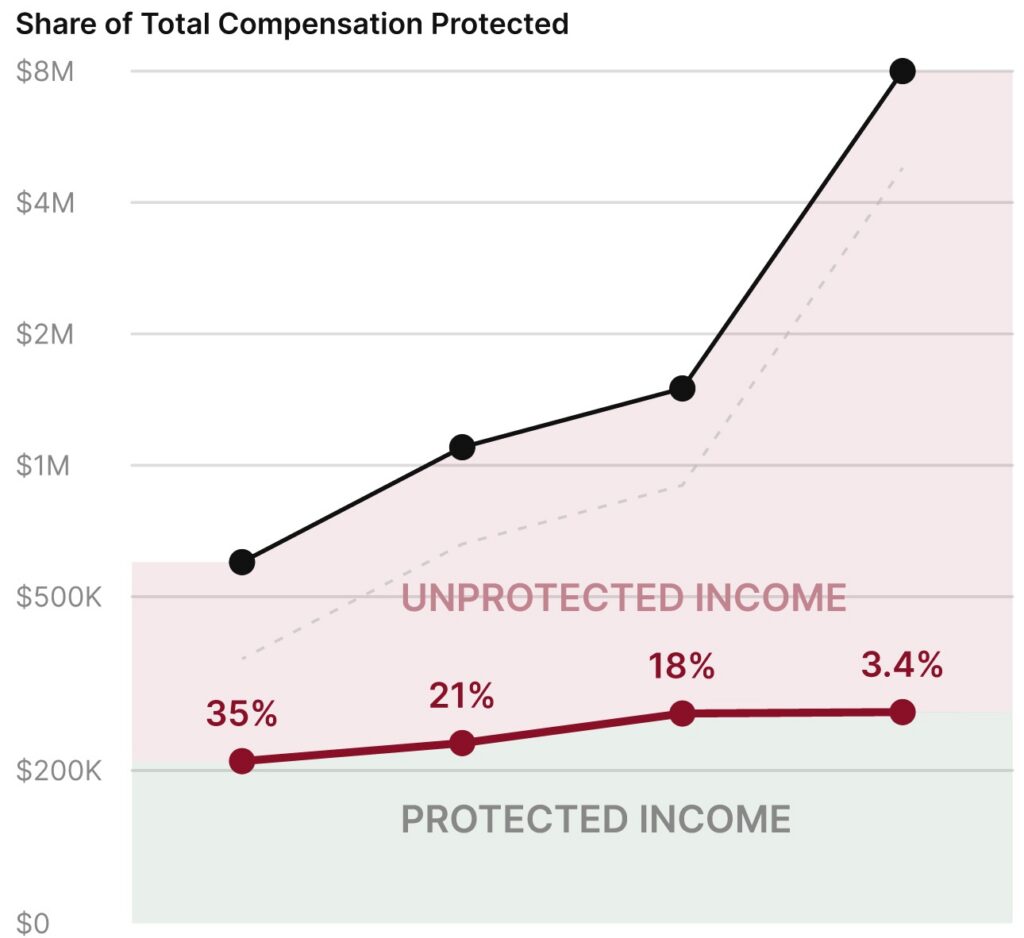
These group disability plans are typically tied to employment status and payroll, meaning benefits may end if training is interrupted. When illness or injury forces time away from work, coverage can disappear alongside the paycheck.
Group plans are also capped at modest benefit levels because intern salaries are low. Travis Christy, chief operating officer of White Coat Insurance Services, a division of White Coat Investor and an agent referral network for physicians, said in his podcast interview that one question comes up often.
“Is my disability through work enough? Which you know we got stories about that, right? Like it typically isn’t. Very rarely is it.”
Travis Christy, chief operating officer, White Coat Insurance Services
Christy tells physicians to treat coverage through work as a bonus and not as a plan.
“you need to go buy your own coverage because that’s not going to be enough if you ever need it.”
Travis Christy, chief operating officer, White Coat Insurance Services
That is his experience and not a measured rate, and he spoke about physicians in general. Some hospitals now offer no-exam guaranteed-issue programs that address part of that shortfall.
By contrast, individual disability insurance for medical residents is owned by the physician, not the employer. Benefits are paid according to policy terms rather than hospital employment rules. That structure can allow coverage to continue through training transitions, leaves or program changes that may otherwise disrupt group benefits.
Definitions of Disability and Early Decisions Shape Resident Coverage
What a disability policy pays depends on how it defines the inability to work. Some policies pay full benefits when a physician cannot perform the material and substantial duties of their occupation, even if other work remains possible. Others require a broader inability to work at all before benefits begin.
The American Medical Association notes that disability insurance policies vary greatly, and that the definition of disability ultimately determines how any claim for benefits will be judged. That makes the definition, along with benefit features and cost, one of the first terms to compare at application.
For residents at institutions without a GSI program, individual coverage is the main route, and residents with no GSI eligibility can pay more for the same coverage.
Long hours, fatigue and emotional strain are built into intern year. Decisions made during training shape income protection not just for the coming year but for the length of a physician’s career.